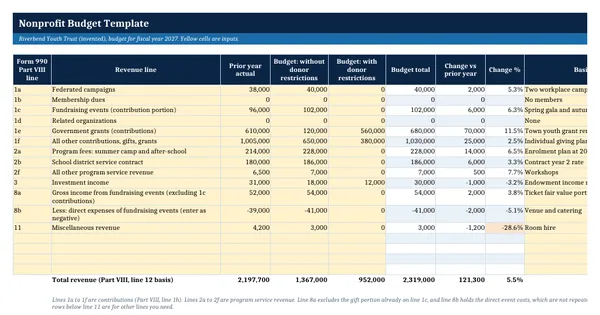
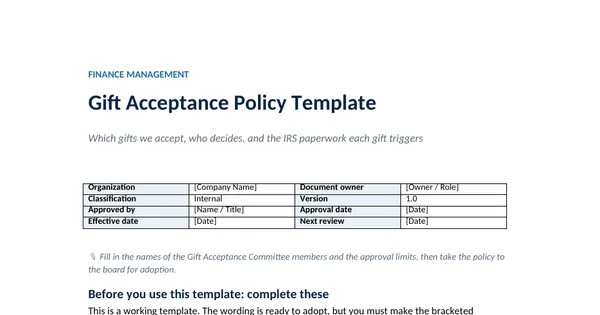
 Word document preview
Nonprofit Financial Policies and Procedures Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A financial policies and procedures manual is the written rulebook for how a nonprofit handles money: who approves a payment, how gifts are received and acknowledged, how restricted grants are tracked and how long records are kept. Auditors read it when they assess internal control, grantors ask for it in due diligence, and Form 990, Part VI asks whether several of these policies exist in writing.
This template is a complete, adoptable manual for a small or mid-size public charity. It maps each Form 990, Part VI governance question to a concrete practice, applies the acknowledgment rules in IRS Publication 1771, and sets approval limits, allocation bases and record retention periods. Retention and filing rules come from IRS Publication 4221-PC, and the allocation rules from the free Form 990 instructions.
Who it is for
The executive director or finance manager of a nonprofit asked by the auditor, a grantor or the board for written financial policies and procedures.
What is inside
- 15 numbered sections: 9 body sections plus purpose, scope, roles, compliance, exceptions and review
- Governance table mapping Form 990, Part VI, Section B lines 11a to 15 to the practice that answers each one
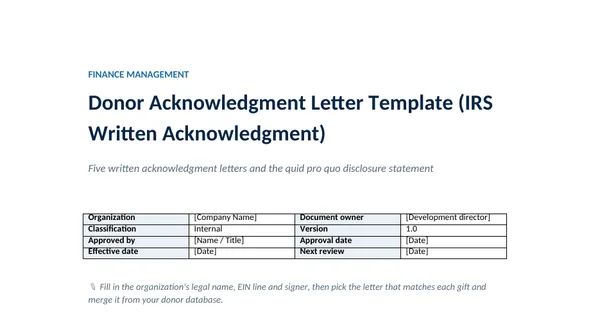
- Donor acknowledgment and quid pro quo disclosure rules from IRS Publication 1771, with the penalty stated
- Purchase and payment approval table with 4 levels, including related-party payments
- Functional expense allocation table with 5 bases and example shares, built on the Form 990 Part IX instructions
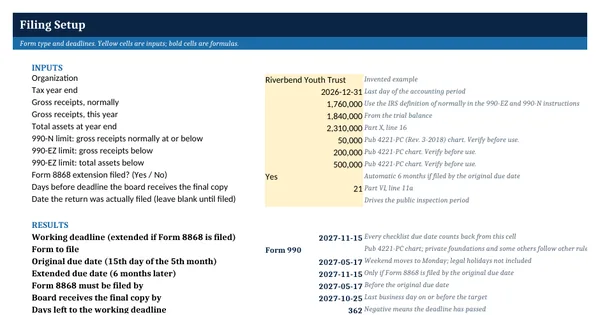
- Records retention table with 5 record types and periods from IRS Publication 4221-PC, plus the Form 990 filing deadline
- Roles table with 6 roles and an adoption checklist with 7 decisions
How to use it
Fill in the approval limits, deposit timing and reporting days, then have the finance committee review the manual before the board adopts it.
Files
- DOCXnonprofit-financial-policies-and-procedures-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Does the IRS require a nonprofit to have written financial policies?
Publication 4221-PC says the Internal Revenue Code does not require charities to have governance and management policies, but the IRS encourages boards to consider them. Form 990, Part VI, Section B still asks whether the organization has a written conflict of interest policy, whistleblower policy and document retention and destruction policy, and how compensation is set.
When must a charity give a donor a written acknowledgment?
IRS Publication 1771 says a donor cannot claim a deduction for any single contribution of USD 250 or more without a contemporaneous written acknowledgment. The acknowledgment names the organization, states the cash amount or describes the property, and says whether goods or services were given in return and, if so, gives a good faith estimate of their value.
How long should a nonprofit keep its financial records?
Publication 4221-PC says records supporting a return are kept until the statute of limitations runs, generally three years after the return is due or filed, whichever is later. Employment tax records are kept at least four years, and organizing documents, the determination letter and board minutes permanently. Grantors and states can require longer.