 Word document preview
Account Reconciliation Policy
3 free downloads per account. Just your email and a 6-digit code.
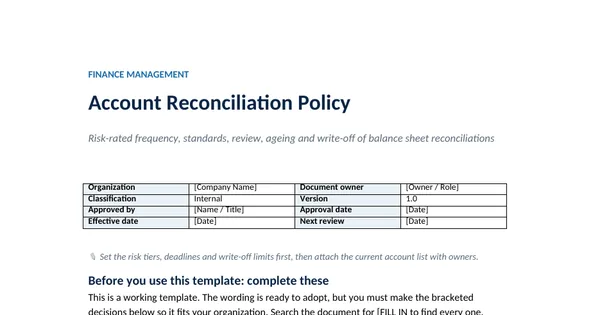
About this template
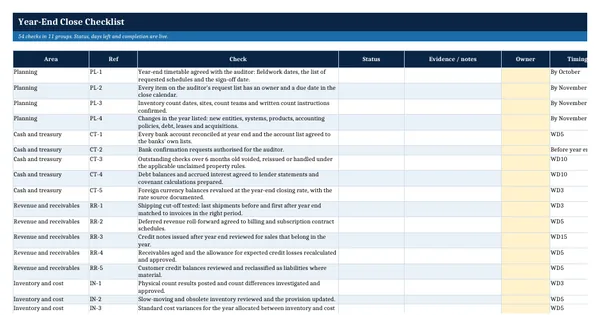
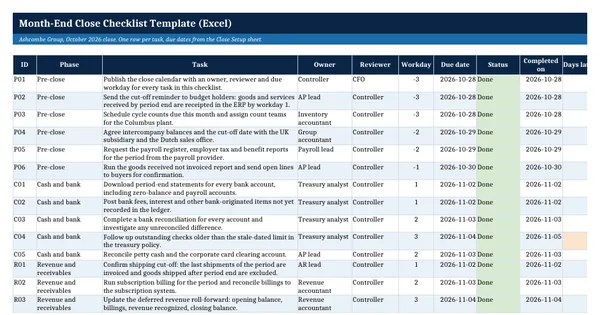
An account reconciliation policy sets how often each balance sheet account is reconciled, what a complete reconciliation contains, who prepares and reviews it, and how old an unexplained item may get. It is needed when reconciliations are late or unsigned, when the auditor asks for the written standard, or when the finance team grows and each person reconciles in their own way.
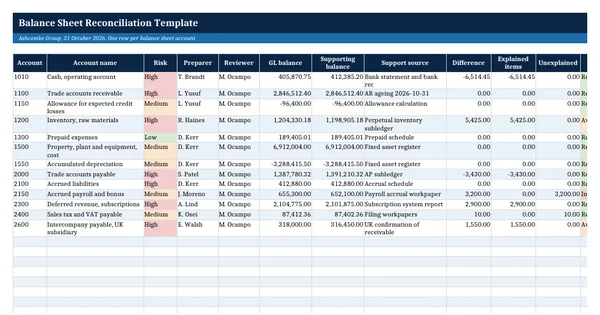
The template has sixteen numbered sections. Accounts are rated high, medium or low risk, and the rating drives frequency, deadline and reviewer. Tables set the ageing bands for reconciling items, the write-off authority and the monitoring metrics. Retention follows IRS record guidance and section 388 of the UK Companies Act 2006. The worked example is Ashcombe Group, an invented company.
Who it is for
The controller whose auditor found unsigned and months-old reconciliations and asked for the written policy that says how often each account is reconciled and by whom.
What is inside
- 16 numbered sections, including roles and a policy close (compliance, exceptions, review)
- Risk rating table: 3 tiers with criteria, example accounts, frequency, deadline and reviewer
- Seven required elements of a complete reconciliation
- Reconciling item ageing table in 4 bands with the action and escalation for each
- Write-off authority table in 4 rows, from accounting manager to CFO
- Monitoring table of 5 metrics with targets and who receives them
- Retention rule from IRS guidance and the UK Companies Act 2006
- Checklist of 7 decisions to make before adoption
How to use it
Set the risk tiers, deadlines and write-off limits first, then attach the current account list with owners.
Files
- DOCXaccount-reconciliation-policy.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Based on general finance practice, not on one published standard. A template to adapt, not legal, tax or accounting advice.
Questions about this template
How often should balance sheet accounts be reconciled?
It depends on risk. In this template high-risk accounts, such as cash, receivables, inventory and intercompany, are reconciled every month by WD5. Medium-risk accounts are reconciled monthly by WD8, and low-risk accounts quarterly. Every account with a balance is reconciled at year end. The risk rating is reviewed each year and when an account changes.
What should a complete account reconciliation contain?
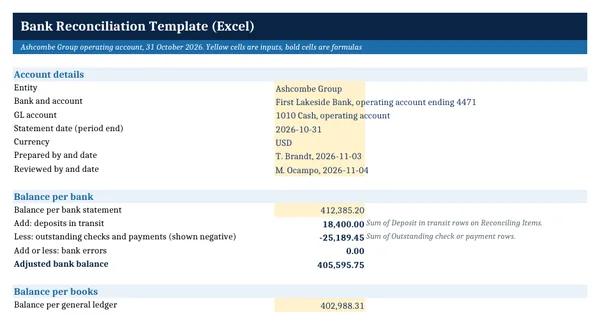
The general ledger balance, an independent supporting balance such as a bank statement or sub-ledger, a list of reconciling items with dates and explanations, an unexplained difference of zero or within the threshold, the support attached, and the preparer and reviewer sign-off with dates.
What happens to old reconciling items?
In this template an item over 30 days old gets an action and an owner, over 60 days goes to the controller, and over 90 days is corrected, written off with approval or reported to the CFO. Old items matter because they hide errors and can turn into losses that should have been recorded earlier.