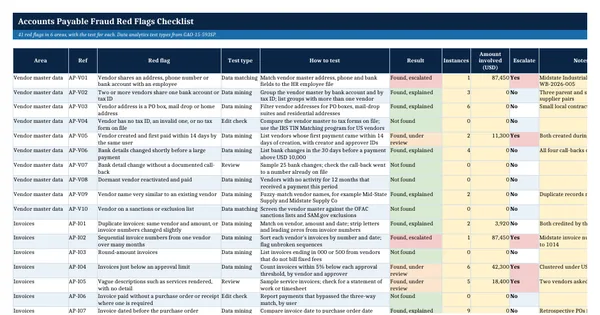
 Excel workbook preview
Accounts Payable Fraud Red Flags Checklist
3 free downloads per account. Just your email and a 6-digit code.
About this template
An accounts payable fraud red flags checklist lists the warning signs of payment fraud, such as fictitious vendors, duplicate invoices, changed bank details, split purchases and payments released by the person who entered them, together with the test that finds each one. Controllers and internal auditors use it for a periodic review and to show the auditor that payables are checked for fraud.
The 41 red flags are grouped in six areas and each has a test type taken from the data-analytics activities in GAO-15-593SP: edit checks, data matching and data mining, plus reviews and observation. Results, instances and amounts feed a live summary per area. The worked example shows a third-quarter review at an invented group, including the fictitious vendor that led to an investigation.
Who it is for
The controller or internal auditor who was asked to show that accounts payable is reviewed for fraud and needs a test list that can actually be run.
What is inside
- 41 red flags in 6 areas: vendor master, invoices, payments, purchasing, people and access, bank
- A test type and a how-to-test step for every red flag (data matching, data mining, edit check, review, observation)
- Result dropdown with 5 outcomes, colored from Not found to Found, escalated
- Escalate formula that marks every open or escalated finding
- Worked third-quarter results for an invented group, with instances and amounts
- 16 blank rows for your own red flags
- Summary per area: tested, found, open or escalated, amount and tested percentage
How to use it
Run the vendor master tests first, then record each result, instance count and amount on the Red Flags sheet.
Files
- XLSXaccounts-payable-fraud-red-flags-checklist.xlsx16 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What are the most common accounts payable fraud red flags?
Vendors that share an address or bank account with an employee, bank details changed just before a payment, duplicate or sequential invoices, invoices just under an approval limit, vague service invoices with no receipt, payments released by the same person who entered them, and staff who never take leave or insist on handling one vendor alone.
Does a red flag mean fraud has happened?
No. Most red flags have an innocent explanation, such as a parent and subsidiary sharing a bank account or a small site with one buyer. The checklist records the explanation as Found, explained, and only open or escalated items go to the fraud risk lead.
How often should accounts payable be tested for fraud?
Many organizations run the data tests every quarter on the full vendor, invoice and payment files, and the review and observation items once or twice a year. GAO-15-593SP suggests automating data-analytic tests to monitor for fraud indicators on a continuous basis where that is practical.