

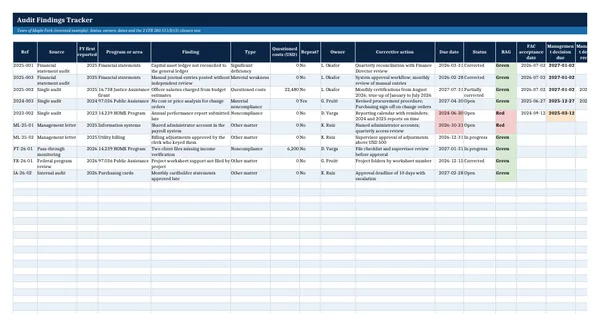
 Excel workbook preview
GAO Yellow Book and Single Audit
Audit Findings Tracker
3 free downloads per account. Just your email and a 6-digit code.
About this template
Findings come from the single audit, the financial statement audit, pass-through monitoring visits, Federal program reviews and internal audit, and each one needs an owner, an action and a date. A finding that is still open next year has to be reported on the summary schedule of prior audit findings, and a repeat finding can affect low-risk auditee status. This tracker is for the person who must keep the list current and report on it.
The register holds every finding in one place with its source, type, questioned costs, owner, corrective action and due date. Formulas set a red, amber or green status, compute when the funding agency's management decision is due under 2 CFR 200.521(d), and test the three conditions in 2 CFR 200.511(b)(3) for reporting a finding as no longer warranting action. The Summary sheet gives the counts a board or audit committee asks for.
Who it is for
The controller or grants compliance manager who must keep every open audit and monitoring finding moving and report status to the board and the auditor.
What is inside
- Findings register with 18 columns and 10 worked rows for an invented town plus 20 blank rows
- Dropdowns for source, finding type, repeat flag, status and agency follow-up
- Formula RAG status from the due date and status, plus red highlighting for overdue items
- Management decision due date computed as six months after FAC acceptance (2 CFR 200.521(d))
- Formula test for the three conditions in 2 CFR 200.511(b)(3)
- Summary sheet: counts by status, type and source, open questioned costs, overdue actions and overdue management decisions
- Freeze panes, filters, print fit and a How to use sheet
How to use it
Enter every open finding from your last single audit, management letter and monitoring visits, one row each, with an owner and a due date.
Files
- XLSXaudit-findings-tracker.xlsx14 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What should an audit findings tracker include?
At least the finding reference, its source and type, the fiscal year it first occurred, the program or area, questioned costs, whether it repeats, the owner, the corrective action, the due date and the status. For single audit findings it also helps to track the FAC acceptance date and the management decision from the funding agency.
When is the funding agency's management decision due?
2 CFR 200.521(d) requires the Federal agency or pass-through entity responsible for the management decision to issue it within six months of the FAC's acceptance of the audit report. The tracker adds six months to the FAC acceptance date you enter and flags decisions that are past that date without a recorded decision.
How does the tracker help with the summary schedule?
Every finding that is not closed carries its status, reasons and planned action, which is what 2 CFR 200.511(b) asks the summary schedule of prior audit findings to report. The closure test column shows when a finding meets all three conditions to be reported as no longer warranting further action.
More GAO Yellow Book and Single Audit templates
Uniform Guidance (2 CFR 200)
Grant Management Policy Template (2 CFR 200)
Uniform Guidance (2 CFR 200)
Procurement Policy Template for Federal Grants (2 CFR 200.318)
Uniform Guidance (2 CFR 200)
Allowable Cost Checklist (2 CFR 200 Subpart E)
Uniform Guidance (2 CFR 200)