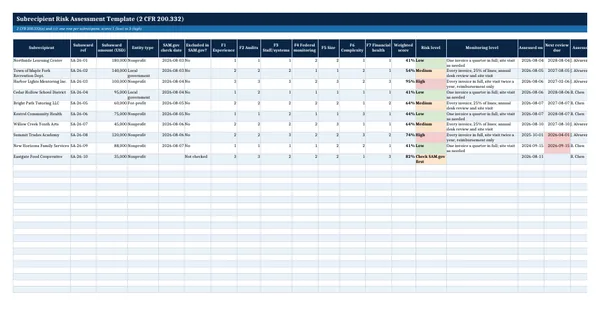
 Excel workbook preview
Subrecipient Risk Assessment Template (2 CFR 200.332)
3 free downloads per account. Just your email and a 6-digit code.
About this template
A subrecipient risk assessment is the record a pass-through entity keeps to show it evaluated each subrecipient's fraud risk and risk of noncompliance before deciding how closely to monitor it. 2 CFR 200.332(c) requires this evaluation and names four things to consider. Auditors look for it whenever an organization passes Federal funds to partners.
This workbook scores each subrecipient on the four factors in 200.332(c), prior experience, audit results, new personnel or systems and Federal agency monitoring, plus three factors the organization adds for size, complexity and financial health. Weights and bands sit on a settings sheet, and the score, risk level, monitoring level and next review date are live formulas. A SAM.gov exclusion check under 200.332(a) overrides the score.
Who it is for
The grants manager at a pass-through entity who must show the auditor how each subrecipient's risk was evaluated before the subaward.
What is inside
- Risk register with 10 worked subrecipients and 20 blank rows
- 7 scored factors: the 4 in 200.332(c) plus 3 of the organization's own
- Weights, risk bands and review intervals in yellow input cells on a Settings sheet
- Live weighted score, risk level, monitoring level and next review date by formula
- SAM.gov exclusion check per subrecipient that overrides the score
- Scoring guide sheet that defines scores 1, 2 and 3 for every factor
- Summary sheet with counts and subaward dollars per risk level and overdue reviews
- Dropdowns, colour bands, overdue highlight, freeze panes and print fit
How to use it
Review the weights and risk bands on the Settings sheet, then replace the worked rows with your own subrecipients.
Files
- XLSXsubrecipient-risk-assessment-template.xlsx17 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What does 2 CFR 200.332 require for subrecipient risk?
Section 200.332(c) requires the pass-through entity to evaluate each subrecipient's fraud risk and risk of noncompliance to decide on the right monitoring. It should consider prior experience with similar subawards, previous audit results including Single Audits, new personnel or new or substantially changed systems, and the extent and results of Federal agency monitoring.
How often should subrecipient risk be reassessed?
The regulation ties the evaluation to each subaward and does not fix an interval. This workbook uses review intervals of 6, 12 and 24 months for high, medium and low risk as editable settings, and a new assessment is made before every new subaward or after a significant development such as an audit finding.
What if a subrecipient is excluded in SAM.gov?
Section 200.332(a) requires the pass-through entity to verify that a subrecipient is not excluded or disqualified, for example by checking SAM.gov. In this workbook an exclusion overrides the score and the risk level shows that no award may be made, and a missing check shows that the check comes first.