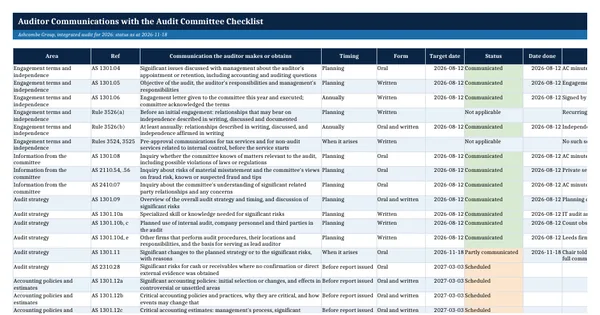
 Excel workbook preview
Auditor Communications with the Audit Committee Checklist
3 free downloads per account. Just your email and a 6-digit code.
About this template
PCAOB AS 1301 sets out what a public company's auditor must discuss with the audit committee: the terms of the engagement, the audit strategy and significant risks, critical accounting policies and estimates, misstatements, disagreements, difficulties and the draft report, all before the report is issued. Other standards and rules add independence, fraud, illegal acts and control deficiency communications. The committee needs a way to see that each one happened and was minuted.
This checklist turns those requirements into 48 short rows in our own words, each with its paragraph reference to the public standard on pcaobus.org, the usual timing, the form and a place to record when it happened and where the evidence is. A summary counts what is still open by area and by timing, so the committee can close every item at the completion meeting.
Who it is for
The audit committee chair, CFO or company secretary who must confirm, before the audit report is issued, that the auditor covered every required communication.
What is inside
- 48 communication items in 9 areas, each with its PCAOB paragraph or rule reference
- Covers AS 1301 plus independence rules, fraud, illegal acts, control deficiencies and related parties
- Timing, form, target date, status, date done and evidence for every item
- Worked example status for an invented company as at 2026-11-18
- Past target dates turn red; status is color coded
- Coverage formula: communicated items over applicable items
- Summary sheet by area and by timing with open and past-due counts
- 6 blank formatted rows for items your auditor or exchange adds
How to use it
Mark items that cannot apply as Not applicable, then enter the target meeting date for the rest.
Files
- XLSXauditor-communications-with-the-audit-committee-checklist.xlsx15 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What must the auditor communicate to the audit committee?
Under PCAOB AS 1301: engagement terms, the audit strategy, timing and significant risks, accounting policies, critical estimates and unusual transactions, the auditor's view of reporting quality, uncorrected and corrected misstatements, the draft report, disagreements and difficulties. Other standards add independence, fraud, illegal acts, related parties and control deficiencies.
When do the communications have to happen?
In a timely manner and before the auditor's report is issued. The right moment depends on how significant the matter is. Planning matters usually go to the first meeting of the cycle, results to the completion meeting, and urgent matters can go to the chair first and to the full committee later.
Do the communications have to be in writing?
Most can be oral or written, but the auditor must document all of them. Some must be written, such as significant deficiencies and material weaknesses and the annual independence communications. The checklist records the form used and where the evidence sits.