

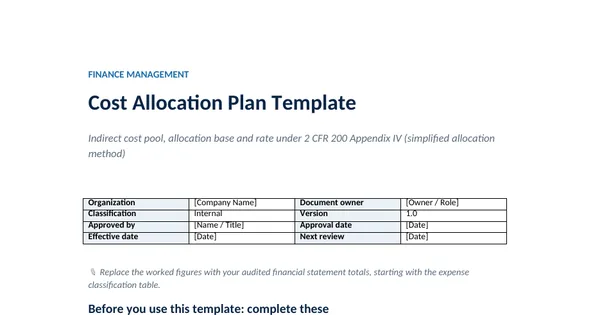
 Word document preview
Cost Allocation Plan Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A cost allocation plan explains how an organization separates its costs into direct and indirect, which costs form the indirect cost pool, which base the pool is spread over and how the resulting rate is charged to Federal awards. Nonprofits need it to support an indirect cost rate proposal to their cognizant agency, to justify the rate they charge a pass-through entity, and to answer auditors who test indirect charges.
This template follows 2 CFR 200.412 to 200.416, the definition of modified total direct costs in 200.1 and Appendix IV to part 200 for nonprofit organizations, as published on eCFR. It uses the simplified allocation method with a fully worked example: expense classification, an indirect cost pool, the MTDC base, the rate computation, application to four funding streams, the de minimis comparison and the submission and certification rules.
Who it is for
The finance director of a nonprofit with Federal awards who must document how indirect costs are allocated before negotiating a rate or answering an auditor.
What is inside
- Simplified allocation method under 2 CFR 200 Appendix IV, section B.2
- Expense classification table with 11 cost lines split into direct and indirect
- Indirect cost pool table with 8 lines, including an applicable credit
- MTDC base and rate computation, with every exclusion in the 200.1 definition
- Rate application to 4 funding streams, including a statutory cap
- Comparison with the de minimis rate and the four rate types
- Submission deadlines and certificate signatory rules from Appendix IV
- Checklist of 8 decisions to make before adoption
How to use it
Replace the worked figures with your audited financial statement totals, starting with the expense classification table.
Files
- DOCXcost-allocation-plan-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What is the difference between a cost allocation plan and an indirect cost rate proposal?
In 2 CFR 200 a cost allocation plan usually refers to central service or public assistance plans of governments under Appendices V and VI, while nonprofits submit an indirect cost rate proposal under Appendix IV. Many nonprofits call the document that supports their proposal a cost allocation plan, and this template is written for that use.
Should a nonprofit use the 15 percent de minimis rate instead?
Under 200.414(f) an organization without a negotiated rate may charge up to 15 percent of modified total direct costs with no documentation, and once elected it must use that rate on all Federal awards until it negotiates one. If the computed rate is clearly higher, as in the worked example, negotiating a rate recovers more of the real cost.
When is an indirect cost rate proposal due?
Appendix IV says a nonprofit without a rate submits its first proposal immediately after it is told an award will be made and no later than three months after the award's effective date. An organization with a rate submits a new proposal within six months after the close of each fiscal year unless an extension was approved.
More Uniform Guidance (2 CFR 200) templates
Uniform Guidance (2 CFR 200)
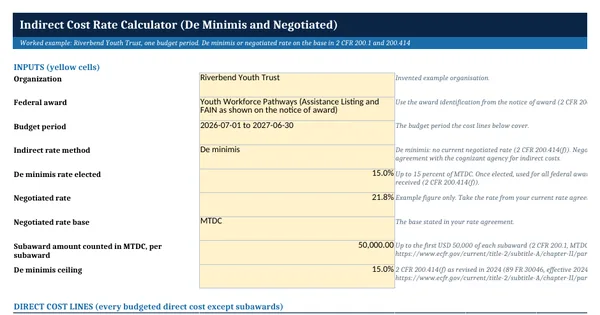
Indirect Cost Rate Calculator (De Minimis and Negotiated)
Uniform Guidance (2 CFR 200)
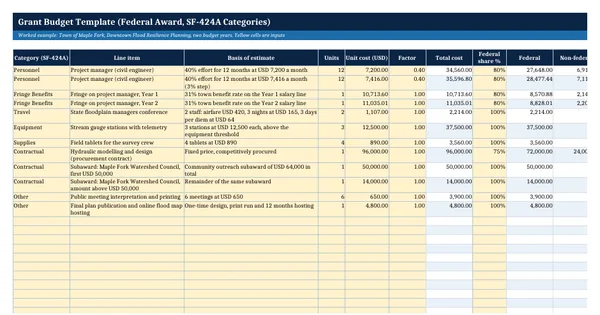
Grant Budget Template (Federal Award, SF-424A Categories)
Uniform Guidance (2 CFR 200)
Grant Drawdown and Expenditure Tracker
Uniform Guidance (2 CFR 200)