 Excel workbook preview
OECD transfer pricing and Pillar Two
Intercompany Transactions Register
3 free downloads per account. Just your email and a 6-digit code.
About this template
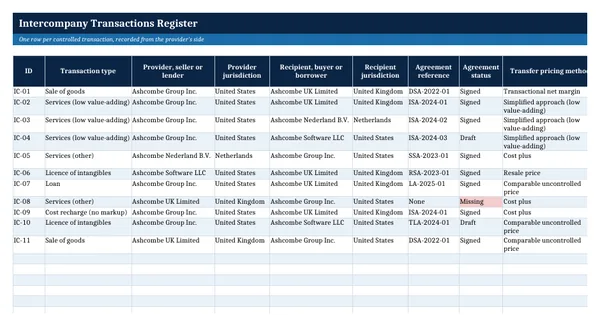
An intercompany transactions register is the single list of every controlled transaction in a group: sales of goods, services, licences, loans and recharges, with the parties, the amounts, the agreement behind each one and how it is priced. Auditors ask for it when they test related party disclosures, and tax authorities ask for it in transfer pricing reviews.
This register is built around the information the local file in Annex II to Chapter V of the OECD Transfer Pricing Guidelines asks for: the category of transaction, the associated enterprises, amounts by counterparty jurisdiction, copies of agreements, the method and the tested party. Formulas add a variance against target, a review countdown and a risk rating.
Who it is for
The controller or group tax lead asked by the auditor or a tax authority for a list of all intercompany transactions, their agreements and their pricing.
What is inside
- Register with 11 worked intercompany transactions and 20 blank formatted rows
- Dropdowns for transaction type, agreement status, transfer pricing method and local file coverage
- Variance between target and actual result, days to the next review and a risk rating, all by formula
- Red risk rating for a missing agreement or a result below target, and red overdue review dates
- Summary sheet with count, amount and missing agreements per transaction type
- Summary of amounts by counterparty jurisdiction, as the OECD local file asks for
- Overall coverage: signed agreements, local file coverage and risk counts
How to use it
Enter every intercompany flow once, from the provider's side, with its agreement reference, method and target, then review the red rows first.
Files
- XLSXintercompany-transactions-register.xlsx14 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What is an intercompany transaction?
It is a transaction between two entities of the same group, for example a sale of goods by a parent to its subsidiary, a service charge, a royalty or an intra-group loan. The OECD Transfer Pricing Guidelines call them controlled transactions and expect them to be priced as independent parties would price them, which is the arm's length principle.
Why keep a register of intercompany transactions?
It gives one complete list for the local files, the Country-by-Country Report, related party disclosures and the year-end intercompany reconciliation. Annex II to Chapter V of the OECD Guidelines asks for amounts per category broken down by the jurisdiction of the counterparty, and for copies of all material intercompany agreements.
Which transfer pricing methods does the register cover?
The dropdown lists the five methods in Chapter II of the OECD Guidelines: comparable uncontrolled price, resale price, cost plus, transactional net margin and transactional profit split, plus the simplified approach for low value-adding services from Chapter VII.