 Excel workbook preview
UK Corporation Tax Computation Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A Corporation Tax computation turns the profit in a company's accounts into the taxable total profits and the tax due for an accounting period. Since April 2023, UK companies pay the 19% small profits rate, the 25% main rate, or the main rate less marginal relief, depending on their profits, their associated companies and the length of the period. Controllers need a computation that shows each step clearly for the auditor, the adviser and the CT600.
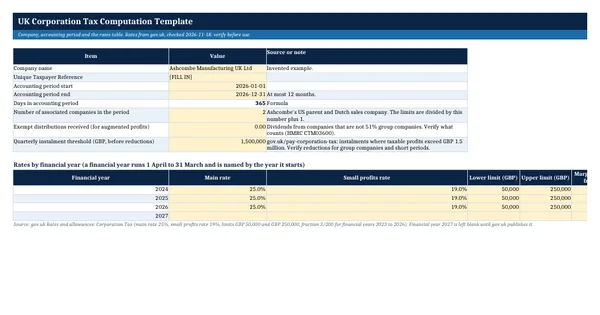
This workbook adds back disallowable items, deducts capital allowances, applies losses and charitable donations, and works out augmented profits. It splits a period that spans 1 April between financial years, scales the limits and applies the marginal relief formula from HMRC's Company Taxation Manual (CTM03925). The rates come from the gov.uk Corporation Tax rates page and sit in input cells, and the worked example is an invented Leeds manufacturer.
Who it is for
The financial controller of a UK company who has to prepare or review the Corporation Tax computation for the auditor or the tax adviser and needs the marginal relief worked correctly.
What is inside
- Computation from profit before tax to taxable total profits with 17 input lines and 10 formula lines
- Losses brought forward capped at the trading profit, and qualifying charitable donations relieved
- Augmented profits with exempt distributions for the marginal relief test
- Tax split by financial year by days, with limits scaled and divided by associated companies plus 1
- Marginal relief by formula, F x (U - A) x N / A, matching HMRC's example in CTM03925
- Rates table for financial years 2024 to 2026 as dated input cells from gov.uk, with a blank row for 2027
- Payment date (9 months and 1 day), return date (12 months), instalment flag and days to payment
How to use it
Enter the accounting period and the number of associated companies on the Inputs sheet, check the rates table on gov.uk, then fill in the yellow cells from the accounts.
Files
- XLSXuk-corporation-tax-computation-template.xlsx12 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What is the Corporation Tax marginal relief formula?
HMRC's Company Taxation Manual, CTM03925, gives marginal relief as F x (U - A) x (N / A), where F is the standard fraction (3/200 for financial years 2023 to 2026), U the upper limit, A the augmented profits and N the taxable total profits. It reduces tax at the main rate for augmented profits between the lower and upper limits.
How do associated companies affect the Corporation Tax rate?
gov.uk says the GBP 50,000 lower limit and GBP 250,000 upper limit are divided by the number of associated companies plus one. With three associated companies the limits become GBP 12,500 and GBP 62,500. They are also reduced in proportion for an accounting period shorter than 12 months. The workbook applies both.
When is Corporation Tax due?
gov.uk says Corporation Tax is due 9 months and 1 day after the end of the accounting period for companies with taxable profits up to GBP 1.5 million, while larger companies pay in instalments. The Company Tax Return is due 12 months after the end of the accounting period. The workbook shows both dates.