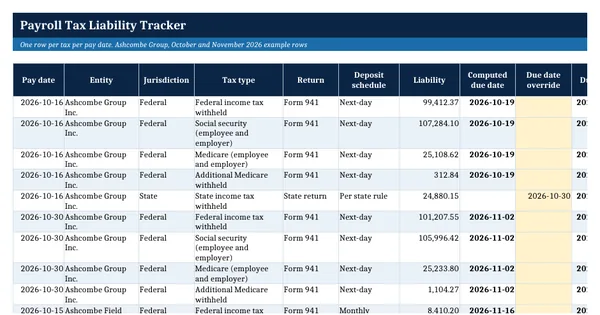
 Excel workbook preview
Payroll Tax Liability Tracker
3 free downloads per account. Just your email and a 6-digit code.
About this template
Withheld income tax, social security and Medicare are trust fund taxes, and IRS Publication 15 states that the trust fund recovery penalty can make responsible people personally liable when they are not paid. Late deposits also carry penalties of their own. A payroll tax liability tracker shows, for each pay date, what was owed, when it was due and when it was paid, so nothing is missed between payroll and treasury.
This tracker calculates due dates from the deposit rules in IRS Publication 15 (2026) and the FUTA rules in the Form 940 instructions, skipping weekends and legal holidays. It compares each deposit with the liability, counts days late and shows an indicative penalty from the published bands. Extra sheets check the USD 100,000 next-day rule, total each month for Form 941 and apply the USD 500 FUTA rule.
Who it is for
The controller or payroll manager who must show that every payroll tax deposit was made on time and in full.
What is inside
- Liabilities sheet with 15 worked rows for two entities and 20 blank rows
- Due date calculated for semiweekly, monthly, next-day and quarterly FUTA schedules, or entered for state taxes
- Status, variance, days late and an indicative penalty from the Publication 15 bands of 2, 5 and 10 percent
- Next-day check that flags any pay date with USD 100,000 or more of Form 941 taxes
- Form 941 liability by month for Part 2 or Schedule B, with the amount deposited
- FUTA quarters sheet that applies the USD 500 deposit rule
- Summary by quarter and tax type, Rules sheet with sources, and a Holidays sheet
- Dropdowns for jurisdiction, tax type, return and deposit schedule, with red, amber and green status colors
How to use it
Enter one row per tax per pay date with its deposit schedule, then add the deposit date and amount when the payment is made.
Files
- XLSXpayroll-tax-liability-tracker.xlsx26 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
When is a payroll tax deposit due?
IRS Publication 15 sets the schedule from the lookback period. Monthly depositors deposit by the 15th of the following month. Semiweekly depositors deposit by the Wednesday or Friday after payday. Any day on which USD 100,000 or more of tax accumulates is due the next business day. Deposits are made by electronic funds transfer.
What is the penalty for a late payroll tax deposit?
Publication 15 lists failure-to-deposit penalties of 2 percent for deposits 1 to 5 days late, 5 percent for 6 to 15 days late, 10 percent for 16 or more days late, and 15 percent for amounts still unpaid more than 10 days after the first IRS notice. The tracker shows the first three bands as an indication only.
When must FUTA tax be deposited?
The Form 940 instructions say that if FUTA tax for a quarter is USD 500 or less, it is carried over to the next quarter. Once the cumulative undeposited amount is more than USD 500, it is deposited by the last day of the month after the quarter ends. The FUTA quarters sheet applies this rule.