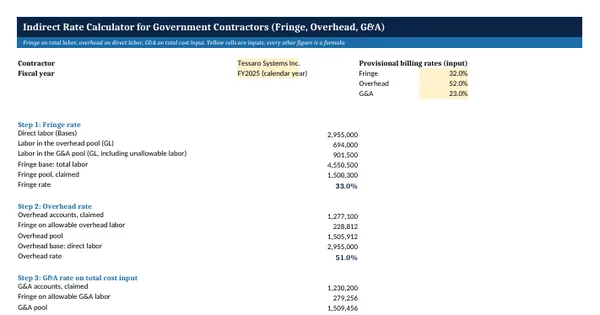
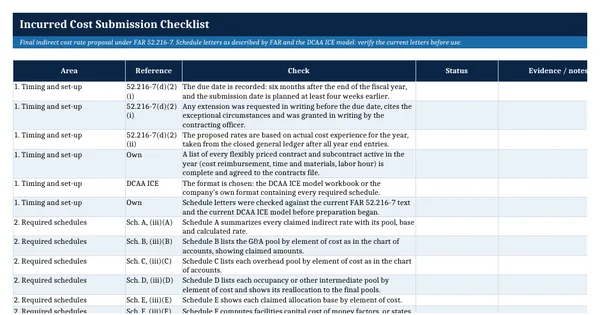
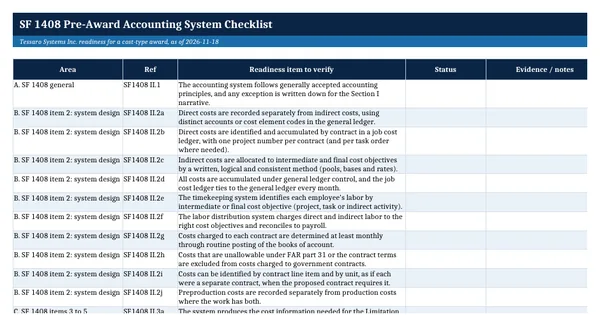
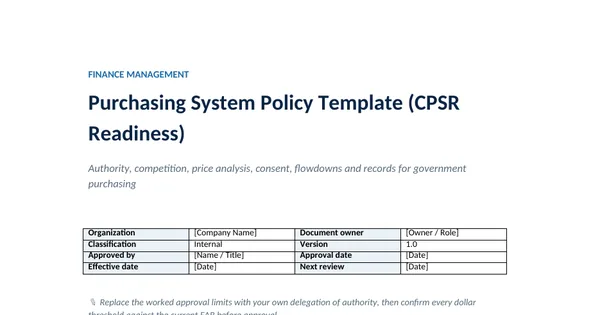
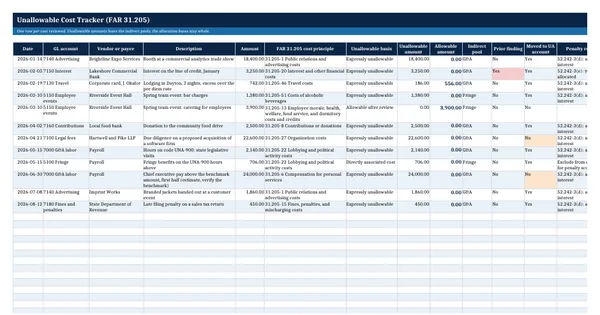
 Excel workbook preview
Unallowable Cost Tracker (FAR 31.205)
3 free downloads per account. Just your email and a 6-digit code.
About this template
Government contractors must identify unallowable costs and keep them, and the costs directly associated with them, out of every billing, claim and proposal. FAR 31.201-6 sets that rule, and an incurred cost submission certified with an expressly unallowable cost in it can draw a penalty under FAR 52.242-3. An auditor will ask how the company finds these costs and where they are recorded. This tracker is that record.
The register logs each cost reviewed, cites the FAR 31.205 subsection, splits the allowable and unallowable amount and records whether the cost has been moved to an unallowable account. A reference sheet lists every subsection of FAR 31.205 with a plain summary of its treatment, and a summary sheet totals unallowable cost by pool and by basis. Everything rests on FAR part 31 and part 52 on acquisition.gov.
Who it is for
The government contractor accountant who must show DCAA how unallowable costs are identified and kept out of indirect rates and billings.
What is inside
- Register with 12 worked sample entries and 20 blank rows, each citing a FAR 31.205 subsection from a dropdown
- Allowable and unallowable split by formula, with a check that flags an unallowable amount larger than the cost
- Penalty reference column that points to FAR 52.242-3(d) or (e) based on the basis and prior determination
- FAR 31.205 Reference sheet listing all 52 subsections, the 6 reserved ones marked, with treatment and what to screen
- Live total of unallowable cost recorded against each FAR 31.205 subsection on the Reference sheet
- Summary sheet by indirect pool and by unallowable basis, with the count of costs not yet moved to an unallowable account
- Dropdowns for basis, pool and yes or no fields, with freeze panes, filters and print fit
How to use it
Delete the sample rows, then log each cost your review flags with its FAR 31.205 subsection and the unallowable amount.
Files
- XLSXunallowable-cost-tracker.xlsx20 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What are expressly unallowable costs?
FAR 31.001 describes an expressly unallowable cost as one specifically named and stated to be unallowable in law, regulation or contract. Examples in FAR 31.205 include entertainment, alcoholic beverages, contributions and donations, interest on borrowings, lobbying, goodwill and fines for violating laws. Including one in a final indirect cost rate proposal can lead to a penalty under FAR 52.242-3.
What is a directly associated unallowable cost?
Under FAR 31.201-6 a directly associated cost is any cost generated solely because another cost was incurred, which would not have been incurred otherwise. When the main cost is unallowable, the directly associated cost is unallowable too. Typical examples are the fringe benefits on time spent lobbying or the travel to an entertainment event.
Does an unallowable cost come out of the allocation base too?
No. FAR 31.203 says that once an allocation base is accepted it may not be fragmented by removing individual elements, and every item properly in the base bears its share of indirect cost whether or not it is accepted as a Government contract cost. Unallowable costs are removed from the indirect pools, not from the base.