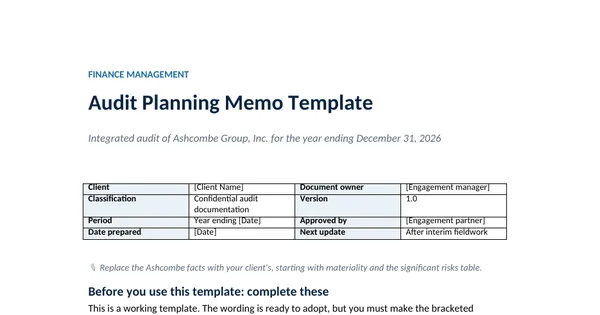
 Word document preview
Audit Planning Memo Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
An audit planning memo records the overall audit strategy: the scope, timing and direction of the audit, and how the plan responds to the risks found. Reviewers and inspectors read it first to see whether the audit was planned around the right risks. It is written before fieldwork starts and updated whenever the risk assessment changes, and the engagement partner signs it off.
This template is a finished memo for an invented accelerated filer with three locations. It covers preliminary engagement activities, business changes, materiality and tolerable misstatement, significant risks with planned responses, location scoping, specialists and service organizations, timing and staffing, audit committee communications and sign-off. It rests on PCAOB AS 2101, AS 2105, AS 2110 and AS 1301, free on pcaobus.org.
Who it is for
The audit manager or senior who must document the overall audit strategy and plan for a public company audit before fieldwork starts.
What is inside
- 10 sections plus purpose and scope, written as a finished memo for an invented client
- 6 worked tables: overview, materiality, risks, locations, timing and approval
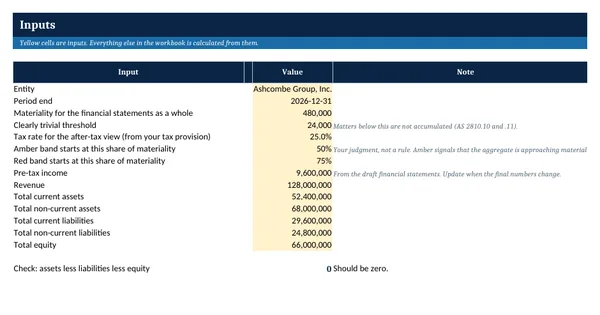
- Materiality, tolerable misstatement and clearly trivial amounts with their basis
- Significant risks table with assertions and planned responses, including the revenue fraud presumption
- Multi-location scoping with another auditor under lead auditor supervision
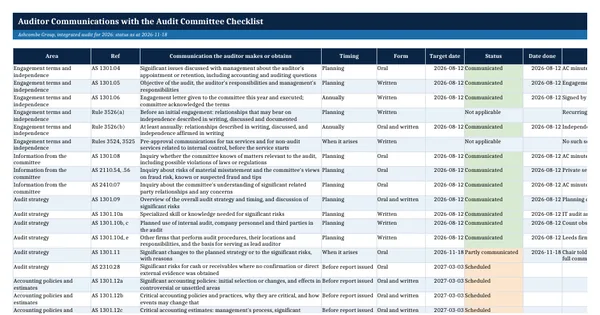
- Audit committee planning and completion communications
- References to the public PCAOB standards AS 2101, AS 2105, AS 2110 and AS 1301
- Checklist of six items to complete before use
How to use it
Replace the Ashcombe facts with your client's, starting with materiality and the significant risks table.
Files
- DOCXaudit-planning-memo-template.docx42 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What goes in an audit planning memo?
The engagement terms and reports to be issued, what changed in the business, materiality and tolerable misstatement, the significant risks and how the audit responds to them, which locations get which procedures, the use of specialists and other auditors, the timetable and staffing, and the planned communications with the audit committee.
Is the memo updated during the audit?
Yes. PCAOB AS 2101 treats planning as continuous and asks the auditor to change the strategy and plan when circumstances change significantly, for example a new risk or a revised risk assessment. Keep the memo current and note what changed and why.
How is materiality chosen in the memo?
The auditor sets an amount for the financial statements as a whole based on earnings and other relevant factors, considers lower amounts for sensitive accounts or disclosures, and sets tolerable misstatement below materiality. The percentages are judgment and the memo records the reasons for them.