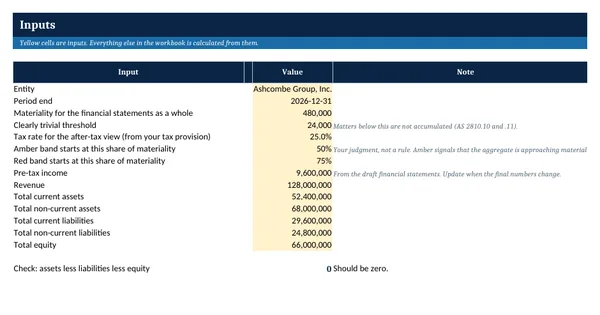
 Excel workbook preview
Summary of Unadjusted Audit Differences Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A summary of unadjusted audit differences lists the misstatements the auditor found that management decided not to correct, with their effect on the financial statements. The auditor must evaluate whether they are material alone or together, give the schedule to the audit committee, and management attaches it to the representation letter. A clear schedule, with the reasons management gives for each item, makes that conversation short and keeps prior-year items from being forgotten.
The workbook records each difference as a balanced correcting entry across six captions, then calculates the pre-tax effect under both the rollover and iron curtain methods, the share of materiality and of each caption, and a color band. A qualitative factors sheet follows PCAOB AS 2810 Appendix B and SEC Staff Accounting Bulletin No. 99, and the two-method test follows SEC Staff Accounting Bulletin No. 108.
Who it is for
The controller or audit senior who must show the audit committee and the representation letter which misstatements stay uncorrected and why they are immaterial.
What is inside
- 11 worked differences (10 uncorrected, 1 corrected) plus 18 blank formatted rows
- Entries by caption with a live check that every entry balances
- Rollover and iron curtain pre-tax effects calculated per item and in total
- Inputs sheet for materiality, clearly trivial, tax rate, band limits and financial statement totals
- Summary sheet with % of each caption, % of materiality, after-tax effect and a Red, Amber, Green band
- Counts of items above clearly trivial, judgmental, projected, prior-year and corrected items
- Qualitative factors sheet with 17 questions from PCAOB AS 2810 Appendix B and SEC SAB 99
- Every output is a live formula off the input cells
How to use it
Enter materiality and the financial statement totals on the Inputs sheet, then record each difference as the entry that would correct it.
Files
- XLSXsummary-of-unadjusted-audit-differences-template.xlsx18 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What is the difference between the rollover and iron curtain methods?
Rollover measures only the part of a misstatement that runs through this year's income statement. Iron curtain measures the full misstatement in the year-end balance sheet as if it were corrected through this year's income. The SEC staff expects both to be considered and a correction when either result is material.
Which misstatements go on the summary?
Every misstatement the auditor accumulated that management has not corrected, other than clearly trivial amounts. That includes known errors, differences on judgmental estimates and projected misstatements from samples. Corrected items are tracked separately because the auditor also reports significant corrected misstatements to the audit committee.
Can uncorrected misstatements below materiality still matter?
Yes. A small amount can be material if it turns a loss into a profit, affects a covenant, increases management's bonus, hides a trend or involves an illegal act. That is why the workbook asks the qualitative questions alongside the amounts.