

 Word document preview
GAO Yellow Book and Single Audit
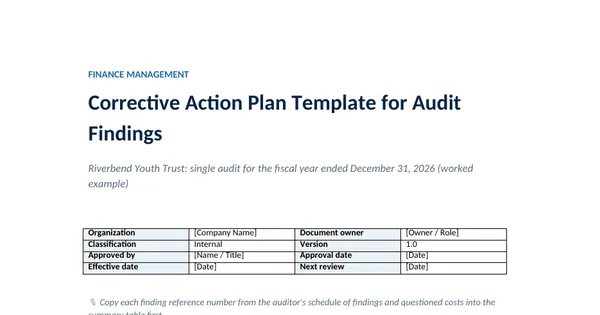
Corrective Action Plan Template for Audit Findings
3 free downloads per account. Just your email and a 6-digit code.
About this template
After a single audit, 2 CFR 200.511(c) requires the auditee to prepare a corrective action plan for every finding in the auditor's report for the current year. The plan is a separate document from the auditor's findings, it is part of the reporting package filed with the Federal Audit Clearinghouse, and Federal agencies and pass-through entities use it when they issue their management decision. This template is for the finance lead who has to write it in the weeks before the filing deadline.
The worked example is an invented youth nonprofit with four findings. Each finding has the contact person, the corrective action and the anticipated completion date the regulation asks for, and one finding shows the detailed explanation required when management does not agree. A monitoring section ties the plan to the next summary schedule of prior audit findings. The structure rests on 2 CFR 200.511, 200.512 and 200.521 and on the GAO Government Auditing Standards 2024 revision.
Who it is for
The finance director who received the auditor's schedule of findings and questioned costs and must submit a corrective action plan with the reporting package.
What is inside
- 10 numbered sections, from purpose and scope to monitoring of progress
- Worked plan for four findings: one financial statement finding and three Federal award findings
- Summary table with reference number, program, response, contact person and anticipated completion date
- A worked disagreement with the detailed explanation 2 CFR 200.511(c) requires
- Monitoring table that links to the next summary schedule of prior audit findings and the management decision
- Notes the GAGAS rule that management, not the auditor, prepares the plan
- Pre-use checklist for adapting names, dates and reference numbers
How to use it
Copy each finding reference number from the auditor's schedule of findings and questioned costs into the summary table first.
Files
- DOCXcorrective-action-plan-template-for-audit-findings.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What must a corrective action plan include?
Under 2 CFR 200.511(c), the plan addresses each audit finding in the auditor's current year report and gives the name of the contact person responsible, the corrective action to be taken and the anticipated completion date. It must use the auditor's reference numbers. When the auditee disagrees or believes no action is needed, the plan includes a detailed explanation of the reasons.
Can the auditor write our corrective action plan?
The plan is management's document. Government Auditing Standards (2024 revision) list an auditor preparing management's corrective action plan as an example of a management participation threat to independence, in paragraph 3.43(d). The auditor can explain a finding, but management decides and writes the response.
When should corrective action start?
2 CFR 200.521(d) says the auditee must initiate and proceed with corrective action as rapidly as possible, and corrective action should begin no later than upon receipt of the audit report. The Federal agency or pass-through entity must issue its management decision within six months of the FAC's acceptance of the audit report.
More GAO Yellow Book and Single Audit templates
GAO Yellow Book and Single Audit
Summary Schedule of Prior Audit Findings Template
GAO Yellow Book and Single Audit
Audit Finding Template (Criteria, Condition, Cause, Effect)
GAO Yellow Book and Single Audit
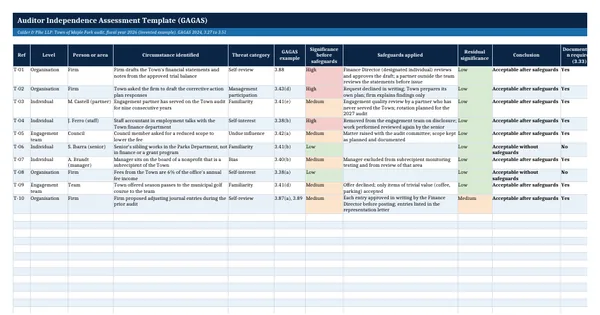
Auditor Independence Assessment Template (GAGAS)
GAO Yellow Book and Single Audit