 Word document preview
GAO Yellow Book and Single Audit
Summary Schedule of Prior Audit Findings Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
Every single audit reporting package includes a summary schedule of prior audit findings prepared by the auditee. 2 CFR 200.511(b) requires it to report the status of all findings in the prior audit's schedule of findings and questioned costs, plus open items carried in the prior summary schedule. The auditor assesses whether it is reasonable, and a schedule that materially misrepresents a finding's status becomes a current year finding. This template is for the person who prepares it.
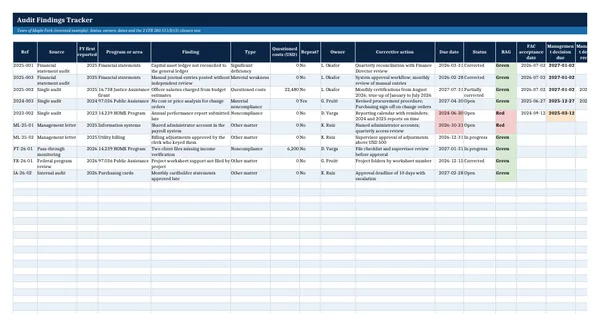
The worked example is an invented town with five prior findings: two fully corrected, one partially corrected, one not corrected and one no longer warranting further action. Each status carries the wording the regulation asks for, including reasons for recurrence and the three conditions in 200.511(b)(3). The template rests on 2 CFR 200.511, 200.514(e) and 200.516(a)(7) and on the GAO Government Auditing Standards 2024 revision.
Who it is for
The finance director preparing the single audit reporting package who must report what happened to last year's findings.
What is inside
- 10 numbered sections, from purpose and scope to questioned costs
- Status rules table for fully corrected, not or partially corrected, and no longer valid findings, by paragraph of 2 CFR 200.511(b)
- Worked schedule for an invented town with five prior findings across three fiscal years
- Partially corrected finding with reasons for recurrence and an explanation where the action differs from the plan
- Three-condition test table for a finding reported as no longer warranting action
- Questioned costs status table
- Pre-use checklist for reference numbers, years and evidence
How to use it
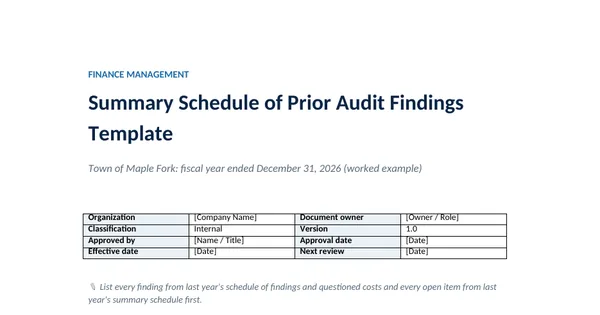
List every finding from last year's schedule of findings and questioned costs and every open item from last year's summary schedule first.
Files
- DOCXsummary-schedule-of-prior-audit-findings-template.docx40 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Which findings go on the summary schedule?
All audit findings in the prior audit's schedule of findings and questioned costs, plus findings reported in the prior summary schedule that are still open. A finding listed last year as corrected, or as no longer valid under 200.511(b)(3), can drop off. Financial statement findings reported under Government Auditing Standards are included too.
When can a prior finding be reported as no longer valid?
2 CFR 200.511(b)(3) accepts it as a valid reason when all three conditions are met: two years have passed since the audit report with the finding was submitted to the FAC, the Federal agency or pass-through entity is not following up, and no management decision was issued. The schedule must describe the reasons.
What does the auditor do with the schedule?
Under 2 CFR 200.514(e), the auditor follows up on prior audit findings and performs procedures to assess the reasonableness of the summary schedule. If it materially misrepresents the status of any prior finding, the auditor reports that as a current year audit finding under 200.516(a)(7).