

 Word document preview
CSRD and ESRS Guide for Finance Teams
3 free downloads per account. Just your email and a 6-digit code.
About this guide
The CSRD changed twice in two years. Directive (EU) 2025/794 postponed reporting for most companies, and Directive (EU) 2026/470 raised the scope to undertakings with more than EUR 450 million net turnover and more than 1,000 employees, added a value chain cap and kept assurance at limited level. Revised ESRS followed in September 2026. Finance teams who prepared under the old rules need to know what still applies and from when.
This guide is dated and states only law published in the Official Journal. It sets out the timeline of the acts, a scope table with first reporting years, the ESRS 2 general disclosures finance usually feeds, double materiality in finance terms, the value chain cap from Delegated Regulation (EU) 2026/1560, connectivity with the financial statements, assurance, the EU Taxonomy key performance indicators and a four-quarter work plan.
Who it is for
The controller or CFO who needs to know, after the 2025 and 2026 changes, whether the CSRD applies, from which year and what the finance team must deliver.
What is inside
- Dated guide stating EU law as published in the Official Journal up to 18 November 2026
- Timeline table of 9 events from the stop-the-clock Directive to the assurance standard deadline
- Scope table for 5 kinds of undertaking with the test and the first financial year
- Table of the ESRS 2 general disclosures with what finance usually supplies
- Plain explanation of the value chain cap, connectivity with the financial statements and limited assurance
- Four-quarter finance work plan table for the next reporting cycle
- 11 numbered sections, about 1,400 words, with every legal act named by its number
How to use it
Read the scope table first to confirm whether and from which year your entity reports, then use the work plan table to schedule the finance tasks.
Files
- DOCXcsrd-and-esrs-guide-for-finance-teams.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this guide
Who is in scope of the CSRD after the Omnibus?
EU undertakings and parent undertakings of groups that exceed both EUR 450 million net turnover and an average of 1,000 employees, from financial years starting on or after 1 January 2027. Non-EU groups report from 2028 if their EU net turnover exceeds EUR 450 million and they have an EU subsidiary or branch above EUR 200 million. National law transposing the change is due by 19 March 2027.
What happens to companies that already reported for 2024?
Wave one companies remain subject to reporting for financial years starting between 1 January 2024 and 31 December 2026. A Member State may exempt those below the new thresholds for 2025 and 2026. From 2027 only those above both thresholds continue. The revised ESRS let wave one companies skip comparatives for changed metrics in their first year under the new set.
When do the revised ESRS apply?
Delegated Regulation (EU) 2026/1563 entered into force on 10 November 2026 and applies to financial years beginning on or after 1 January 2027. For 2026 a company may apply the old set as amended in 2025, the revised set, or the old set with eight listed reliefs, and must say which it used.
More CSRD, ESRS and EU Taxonomy templates
GHG Protocol carbon accounting
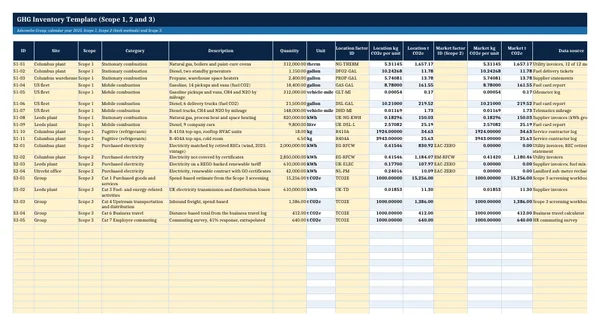
GHG Inventory Template (Scope 1, 2 and 3)
GHG Protocol carbon accounting
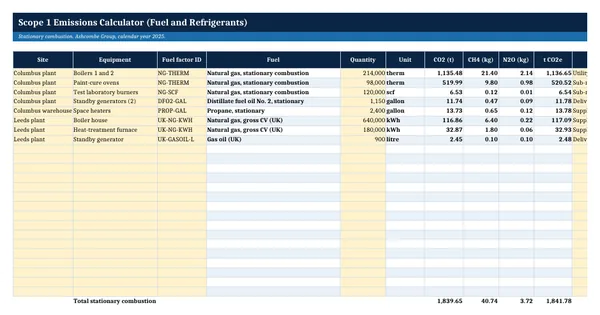
Scope 1 Emissions Calculator (Fuel and Refrigerants)
GHG Protocol carbon accounting
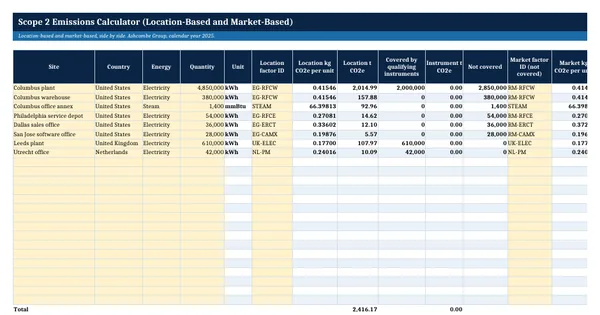
Scope 2 Emissions Calculator (Location-Based and Market-Based)
GHG Protocol carbon accounting