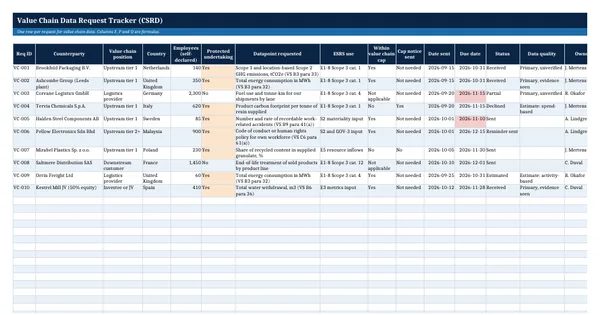
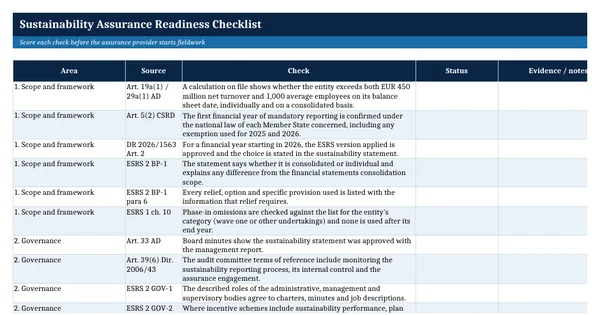
 Word document preview
CSRD Readiness Plan Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A CSRD readiness plan sets out how a company will produce its first sustainability statement under the Corporate Sustainability Reporting Directive: who does what, by when, with which data and controls, and how the statement will be ready for limited assurance. Boards and audit committees ask for it as soon as the company knows it is in scope, because the first reporting year starts long before the report is due.
The plan is built on the CSRD as amended by Directive (EU) 2025/794 and Directive (EU) 2026/470, which set the thresholds of more than EUR 450 million net turnover and more than 1,000 average employees, and on the revised ESRS adopted on 3 July 2026 for financial years from 2027. It contains the scope test, a dated milestone table with sources, a current state assessment, the materiality approach, data and control work, workstreams, assurance preparation and risks.
Who it is for
The CFO or controller who was told by the board that the company falls under the CSRD and needs a credible plan for the first sustainability statement.
What is inside
- 10 body sections, from scope test and timeline to budget and risks
- Scope test on the Omnibus I thresholds: net turnover above EUR 450 million and more than 1,000 employees
- Milestone table with official dates and their legal sources
- Current state assessment table with 6 rated areas
- Workstream table with 9 workstreams, leads, deliverables and due dates
- Plan risks table with 5 risks and mitigations
- Roles and responsibilities table and an adoption checklist
- Worked example for an invented Dutch manufacturer reporting from the 2027 financial year
How to use it
Run the scope test in section 3 with your own consolidated figures before you adapt the timeline.
Files
- DOCXcsrd-readiness-plan-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Which companies are in scope of the CSRD after the Omnibus I changes?
Directive (EU) 2026/470 limits mandatory reporting to undertakings, and parent undertakings on a consolidated basis, that exceed a net turnover of EUR 450 million and an average of 1,000 employees during the financial year. Separate rules apply to third-country groups with large EU turnover. Member States must transpose the changes by 19 March 2027, so check the national law as well.
When does a company that is newly in scope report for the first time?
Under the CSRD as amended, undertakings outside the first wave report for financial years starting on or after 1 January 2027, so the first statement is published in 2028 with the management report. The revised ESRS also apply from financial years beginning on or after 1 January 2027.
Does the sustainability statement need external assurance?
Yes. The statutory auditor, or another assurance provider where the Member State allows it, gives an opinion based on a limited assurance engagement. Directive (EU) 2026/470 requires the Commission to adopt limited assurance standards by 1 July 2027. The plan therefore includes a dry run and an evidence file.