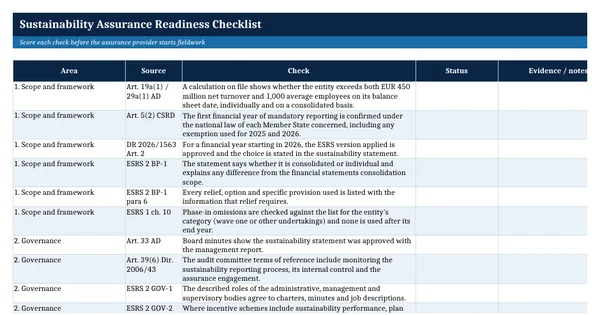
 Excel workbook preview
Sustainability Assurance Readiness Checklist
3 free downloads per account. Just your email and a 6-digit code.
About this template
Companies within the CSRD must have their sustainability statement checked by an assurance provider, who gives a limited assurance opinion on compliance with the ESRS, on the process used to identify the reported information, on the mark-up requirement and on the EU Taxonomy disclosures. For a first engagement the provider asks for a great deal of evidence at once. This checklist shows, area by area, whether that evidence exists before fieldwork starts.
It holds 51 specific checks in nine groups: scope and framework, governance, double materiality, value chain, data and estimates, internal control, EU Taxonomy, presentation and the engagement itself. Each check cites its open source, such as Article 34 of Directive 2013/34/EU as amended, Directive (EU) 2026/470 or a paragraph of the revised ESRS in Delegated Regulation (EU) 2026/1563. A timeline sheet dates the milestones from your year end.
Who it is for
The controller preparing for the first limited assurance engagement on the sustainability statement who needs to know what the assurance provider will ask for.
What is inside
- 51 checks in 9 groups, each tied to an article of the CSRD texts or a paragraph of the revised ESRS
- Status dropdown (Ready, Partly ready, In progress, Not ready, Not applicable) with colour coding
- Live readiness percentage that excludes items marked Not applicable
- Summary sheet with ready items per group and a total
- Timeline sheet that turns your financial year end and offsets into 10 dated milestones
- Days-to-go formula per milestone, overdue dates in red and a deadline headroom check
- Evidence and owner columns for every check, plus a How to use sheet
How to use it
Enter your financial year end and publication deadline on the Timeline sheet, then score each check with the person who owns it.
Files
- XLSXsustainability-assurance-readiness-checklist.xlsx15 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What level of assurance does the CSRD require?
Limited assurance. Directive (EU) 2026/470 removed the earlier power to move to reasonable assurance later. The provider expresses an opinion based on a limited assurance engagement on ESRS compliance, the process to identify reported information, the mark-up requirement and the Taxonomy disclosures under Article 8 of Regulation (EU) 2020/852.
Which assurance standard will the provider use?
The Commission must adopt limited assurance standards by delegated act no later than 1 July 2027. Until it does, Member States may apply national assurance standards, procedures or requirements. Ask your provider which standard applies in your Member State and record it in the engagement letter check.
Who can give the assurance opinion?
The statutory auditor of the financial statements by default. A Member State may also allow another statutory auditor or an accredited independent assurance services provider. Check the national law that transposes the CSRD in each country where you report.