

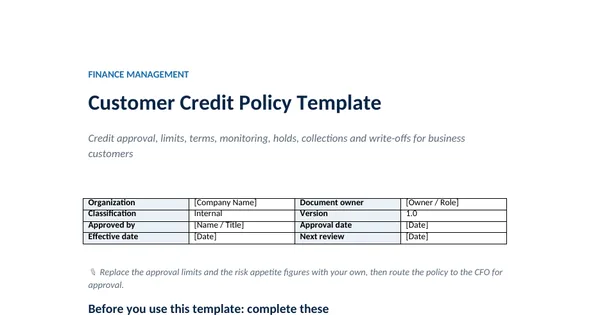
 Word document preview
Order-to-cash and accounts receivable
Customer Credit Policy Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
A customer credit policy is the written rulebook for selling on account to business customers. It says who may approve a credit limit and up to what amount, what evidence a new customer must provide, which payment terms apply, when orders go on hold and how overdue accounts are escalated and written off. Auditors ask for it when they test the allowance for credit losses, and banks ask for it when receivables secure a borrowing line.
This template is written as an adoptable policy for a mid-size group with a US parent, a UK subsidiary and a Dutch sales office. It contains approval and write-off authority tables, a five-level risk rating, a collection timeline and late payment terms per country. The legal points rest on open official texts: Regulation B (12 CFR 1002), 15 U.S.C. 1692a for the Fair Debt Collection Practices Act, the gov.uk late payment guide and Directive 2011/7/EU.
Who it is for
The controller or credit manager who was asked by the auditor, the bank or a new CFO for the written rules on who gets credit, how much and on what terms.
What is inside
- 16 numbered sections, including roles, compliance, exceptions and review
- Approval authority table with new limit, increase and over-limit release levels for 4 approvers
- Five-level customer risk rating with terms, security and review frequency
- Standard terms and late payment charges for a US parent, a UK subsidiary and a Dutch office
- Seven-step collection timeline from 5 days before due to day 90 referral
- Credit decision notices written to Regulation B (12 CFR 1002.9) for business credit
- Write-off authority by amount and the monthly allowance review
- Pre-use checklist of 7 decisions with [FILL IN] examples
How to use it
Replace the approval limits and the risk appetite figures with your own, then route the policy to the CFO for approval.
Files
- DOCXcustomer-credit-policy-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Based on general finance practice, not on one published standard. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What should a credit policy include?
A credit policy should name who approves credit limits and up to what amount, the evidence needed for a new account, the standard payment terms, the security asked from weaker customers, the triggers for a credit review and an order hold, the collection steps by day past due, and who approves write-offs. This template covers each of these in its own section, with worked tables you can edit.
Does the Fair Debt Collection Practices Act apply to business customers?
The act defines a debt as an obligation of a natural person for personal, family or household purposes, and a debt collector as someone who collects debts owed to another. A creditor that collects its own debts under a different name that suggests a third party is also covered. A business collecting its own trade receivables in its own name is generally outside it, but check with counsel.
Do credit decisions for business customers need a notice?
Yes. Regulation B at 12 CFR 1002.9(a)(3) covers business credit. For applicants with gross revenues of USD 1 million or less, the creditor tells the applicant the action taken and of the right to a statement of reasons. For larger businesses and trade credit, notice comes within a reasonable time, and written reasons follow if requested within 60 days.
More Order-to-cash and accounts receivable templates
Order-to-cash and accounts receivable
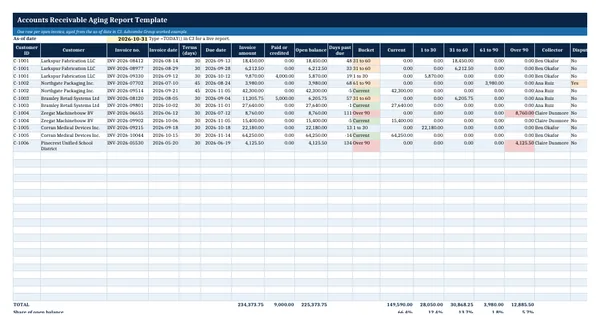
Accounts Receivable Aging Report Template
Order-to-cash and accounts receivable
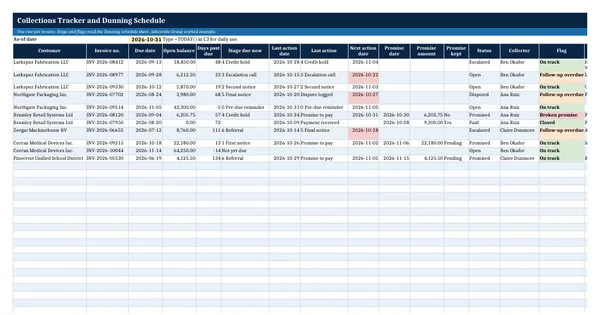
Collections Tracker and Dunning Schedule
Order-to-cash and accounts receivable
Collection Letter Templates (First, Second and Final Notice)
Order-to-cash and accounts receivable