

 Word document preview
UK Corporate Governance Code and FRS 102
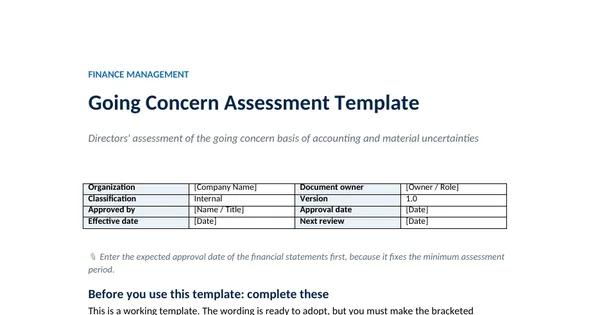
Going Concern Assessment Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
Every company must assess whether the going concern basis of accounting is appropriate when it prepares its financial statements, and whether material uncertainties exist that should be disclosed. In the UK the minimum period is 12 months from the date the financial statements are authorised for issue. Auditors expect to see the assessment written down, with the forecasts, scenarios and judgements behind it, and listed companies make a statement under Provision 30 of the UK Corporate Governance Code.
This template is a complete board paper for an invented UK subsidiary, Ashcombe Manufacturing UK Limited. It records the basis of the assessment, the position at the balance sheet date, the chosen period, a base case, downside scenarios, a reverse stress test, mitigating actions, reliance on group support and the conclusion with draft disclosure. It follows the free FRC Guidance on the Going Concern Basis of Accounting and Related Reporting (February 2025).
Who it is for
The financial controller or finance director of a UK company whose auditor asked for a documented going concern assessment before the accounts can be signed.
What is inside
- 11 numbered sections, written as a board paper for a large private company preparing accounts for the year ended 31 December 2026
- Balance sheet date position table with 8 measures, current and prior year
- Assessment period reasoning that runs past the minimum 12 months to cover a facility maturity
- Quarterly base case headroom and covenant table over 7 quarters
- Downside table with 5 scenarios, including a combined severe but plausible case before and after mitigation
- Reverse stress test, mitigating actions table and an assessment of a parent company letter of support
- Table of the 4 reporting outcomes from the FRC guidance and draft basis of preparation wording
How to use it
Enter the expected approval date of the financial statements first, because it fixes the minimum assessment period.
Files
- DOCXgoing-concern-assessment-template.docx42 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What period does a going concern assessment cover?
The FRC guidance of February 2025 says that in the UK the minimum period is 12 months from the date the financial statements are authorised for issue. A longer period can be more appropriate when a significant event falls just beyond that, such as a loan maturity, a covenant test or the expiry of a key contract. The directors choose the period and explain it.
What are the possible outcomes of the assessment?
The FRC guidance describes four reporting scenarios: the going concern basis is appropriate with no material uncertainties; it is appropriate with no material uncertainties but reaching that view involved significant judgement; it is appropriate but material uncertainties exist and are disclosed; or it is not appropriate and another basis is used. Each scenario carries its own disclosures.
Is a parent company letter of support enough?
A letter of support helps, but the directors still assess whether the parent is able to provide the support it promises, for example by reviewing the parent's own liquidity and forecasts. They also weigh whether the letter is a binding commitment or a statement of intent. This template records that assessment as a separate step in the paper.
More UK Corporate Governance Code and FRS 102 templates
UK Corporate Governance Code and FRS 102
Viability Statement Working Paper Template
UK Corporate Governance Code and FRS 102
Section 172 Statement Template
UK Corporate Governance Code and FRS 102
Audit Committee Terms of Reference Template (UK)
UK Corporate Governance Code and FRS 102