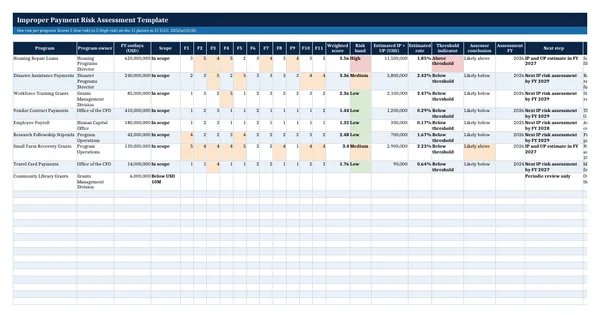
 Excel workbook preview
Improper Payment Risk Assessment Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
An improper payment risk assessment decides whether a program is likely to make improper payments plus unknown payments above the statutory threshold. The Payment Integrity Information Act of 2019 requires federal agencies to review programs with outlays above USD 10 million at least once every three fiscal years, and the inspector general reviews the method. This workbook is for the person who has to run and document that assessment.
The workbook follows Appendix C to OMB Circular A-123 (M-21-19) and 31 U.S.C. 3352. Each program is scored on the eleven statutory risk factors with weights the agency can change. The estimate is tested against the statutory threshold, and a formula shows the next step for the program. The threshold values sit in labelled input cells with their source. The programs and figures are invented examples.
Who it is for
The payment integrity lead or CFO office analyst who has to document the improper payment risk assessment for each program before the inspector general reviews it.
What is inside
- Assessment sheet with 9 worked programs and 16 blank formatted rows
- Scores for all 11 risk factors in 31 U.S.C. 3352(a)(3)(B), with adjustable weights
- Live weighted score and High, Medium or Low band per program
- Statutory threshold test on the estimate: above USD 10 million and 1.5 percent, or above USD 100 million
- Next step formula: an improper and unknown payment estimate next year, or the next assessment within three years
- Flag where the assessor conclusion disagrees with the threshold indicator
- Threshold Test calculator sheet, Risk Factors sheet and a formula-driven Summary sheet
- Dropdowns, colour bands, freeze panes, filters and print fit
How to use it
List every program with its annual outlays on the assessment sheet, then score the 11 risk factors for each program in scope.
Files
- XLSXimproper-payment-risk-assessment-template.xlsx18 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Which programs need an improper payment risk assessment?
Under 31 U.S.C. 3352 and Appendix C to OMB Circular A-123, each program with annual outlays above USD 10 million needs an improper payment risk assessment at least once every three fiscal years, unless it is already in Phase 2 and reporting an estimate. A significant change in law or funding can trigger an off-cycle assessment.
What is the statutory threshold for significant improper payments?
The statute treats improper payments plus unknown payments as significant if they may have exceeded both USD 10 million and 1.5 percent of program outlays, or USD 100 million regardless of the rate. The workbook keeps these values in input cells so they can be checked against the current statute.
Can the risk assessment be qualitative?
Yes. Appendix C says the assessment may be qualitative or quantitative, as long as the method reasonably supports the conclusion. It lists eleven factors that can be considered, which match the statute. This workbook scores those factors and adds an estimate of improper and unknown payments to test against the threshold.