 Excel workbook preview
OECD transfer pricing and Pillar Two
Pillar Two Transitional CbCR Safe Harbour Calculator
3 free downloads per account. Just your email and a 6-digit code.
About this template
The Transitional CbCR Safe Harbour lets a group subject to the Pillar Two GloBE Rules treat the top-up tax in a jurisdiction as zero for a transition period, if the jurisdiction passes one of three tests built on its qualified Country-by-Country Report: a de minimis test, a simplified effective tax rate test or a routine profits test. Tax teams use it to cut the number of full calculations.
This workbook applies the three tests as set out in the OECD Safe Harbours and Penalty Relief document (December 2022), with the one-year extension and the 17% rate for 2027 agreed in the OECD Side-by-Side Package of January 2026. It also checks the qualified CbC report condition, the once out, always out rule and the transition period dates.
Who it is for
The group tax lead who must show, jurisdiction by jurisdiction, which countries qualify for the transitional safe harbour and which need a full GloBE calculation.
What is inside
- Tests sheet with 11 worked jurisdictions and 14 blank formatted rows
- Simplified covered taxes and simplified ETR by formula from the income tax expense, less non-covered taxes and uncertain tax positions
- De minimis test including the exclusion for entities held for sale
- Routine profits test against the substance-based income exclusion at the Article 9.2 transition rates
- Once out, always out check and a qualified CbC report check per jurisdiction
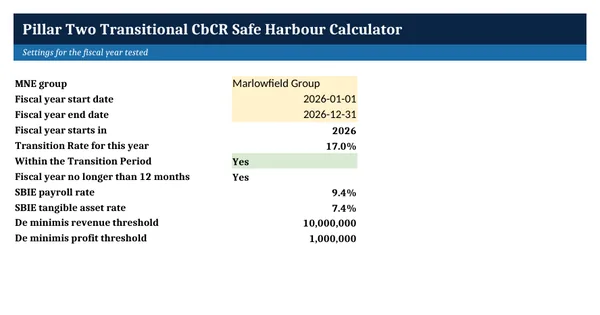
- Settings sheet that tests whether the fiscal year falls in the transition period as extended in January 2026
- Rates sheet with transition rates for 2023 to 2027 and a Summary sheet counting results
How to use it
Set the fiscal year dates on the Settings sheet, check the Rates sheet against the OECD text, then enter each jurisdiction's qualified CbC report figures on the Tests sheet.
Files
- XLSXpillar-two-transitional-cbcr-safe-harbour-calculator.xlsx17 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What are the three tests of the Transitional CbCR Safe Harbour?
The OECD Safe Harbours document lists a de minimis test (total revenue below EUR 10 million and profit before income tax below EUR 1 million), a simplified ETR test (simplified covered taxes divided by profit before tax at or above the transition rate) and a routine profits test (profit before tax at or below the substance-based income exclusion). Passing one is enough.
What are the simplified ETR transition rates?
The December 2022 OECD text sets 15% for fiscal years beginning in 2023 and 2024, 16% for 2025 and 17% for 2026. The Side-by-Side Package of January 2026 extended the safe harbour by one year and applies the 17% rate to fiscal years beginning in 2027 as well. Check local law for the version in force.
What does once out, always out mean?
The OECD Safe Harbours document says that if a group has not applied the Transitional CbCR Safe Harbour to a jurisdiction in a year in which it was subject to the GloBE Rules, it cannot qualify for that safe harbour for that jurisdiction in a later year. The workbook asks for this history per jurisdiction.