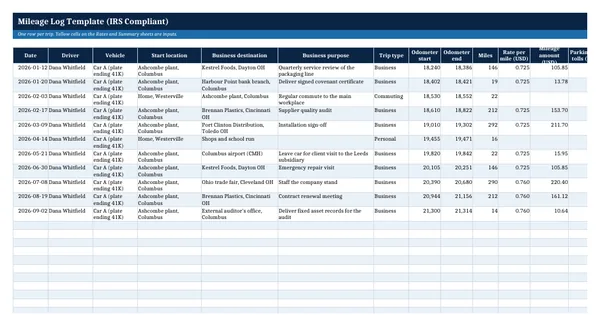
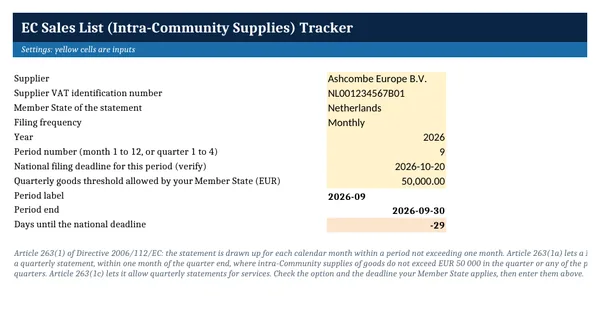
 Excel workbook preview
EC Sales List (Intra-Community Supplies) Tracker
3 free downloads per account. Just your email and a 6-digit code.
About this template
An EC Sales List, called a recapitulative statement in the EU VAT Directive, lists every customer in another Member State to whom a business made intra-Community supplies of goods or B2B services where the customer pays the VAT. Article 138(1a) makes the exemption for an intra-Community supply depend on it: if the statement is missing or wrong, the zero rate can be lost unless the supplier can justify the shortcoming.
This workbook records each supply with the customer's VAT number and VIES result, works out the chargeable date and the reporting period, and totals the values per VAT number for the chosen month or quarter. Credit notes go in the period the customer was notified. It is built on Articles 67, 138 and 262 to 264 of Council Directive 2006/112/EC.
Who it is for
The accounts receivable or VAT accountant who files the recapitulative statement (EC Sales List) and must prove that every zero-rated intra-Community supply is listed with a valid customer VAT number.
What is inside
- Transactions sheet with 12 worked supplies and 24 blank rows: chargeable date under Article 67, reporting period, VIES and invoice timing checks by formula
- Customers sheet that builds the statement for the chosen period: goods, services, triangulation, adjustments and a count of call-off stock transfers per customer VAT number
- Adjustments sheet for credit notes, declared in the period the customer was notified (Article 264(2))
- Reconciliation sheet that ties the statement to the VAT return and checks every transaction reached the statement
- Quarterly filing test over the current and previous four quarters against the EUR 50 000 Member State option in Article 263(1a)
- Settings sheet with monthly or quarterly frequency, the period and the national deadline as a verify-before-use input
- How to use sheet with the Articles 262 to 264 rules
How to use it
Set the frequency and period on the Settings sheet, enter each intra-Community supply on the Transactions sheet, then read the statement lines from the Customers sheet.
Files
- XLSXec-sales-list-tracker.xlsx23 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What is an EC Sales List?
It is the recapitulative statement in Articles 262 to 264 of the VAT Directive. It shows the supplier's VAT number, each customer's VAT number in another Member State, and the total value of goods and services supplied to each customer in the period. Tax authorities use it to check that the customer declares the acquisition.
Is the EC Sales List monthly or quarterly?
Article 263 says it is drawn up for each calendar month. Member States may allow a quarterly statement where intra-Community supplies of goods do not exceed EUR 50 000 in the quarter or in any of the previous four quarters, and may allow quarterly statements for services. Check your national rule and deadline.
What happens if the customer's VAT number is invalid?
Article 138(1) only exempts the supply when the customer is identified for VAT in another Member State and has given that number to the supplier. Without a valid number the exemption is at risk, so the tracker flags any supply whose number was not confirmed as valid in VIES before it is listed.