 Word document preview
VAT Policy and Procedures Manual
3 free downloads per account. Just your email and a 6-digit code.
About this template
A VAT policy and procedures manual is the written record of how a business handles VAT: who is registered where, which tax codes exist, how invoices are issued, how customer VAT numbers are checked, how returns are prepared and how errors are corrected. Auditors, tax inspectors and new finance staff ask for it, and it is the first thing a tax control framework review looks at.
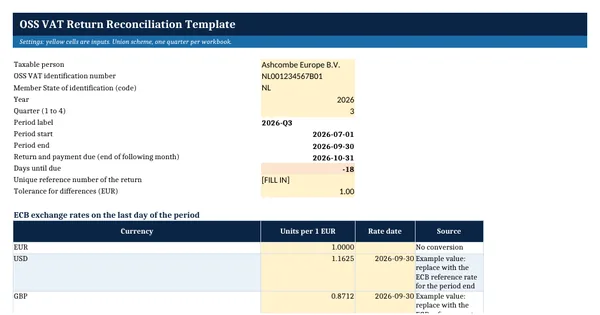
This manual is written for a group with an EU entity that sells goods and services to businesses and consumers across the EU. It covers registrations, tax codes, invoicing, VIES checks, input VAT recovery, cross-border rules, the One Stop Shop, a monthly return calendar, corrections and record keeping. Each rule cites Council Directive 2006/112/EC or the Commission's Guide to the VAT One Stop Shop.
Who it is for
The group tax manager or controller who was told by the auditor or a new CFO that nobody has written down how VAT is handled across the EU entities.
What is inside
- 10 body sections plus purpose, scope, roles, compliance, exceptions and review
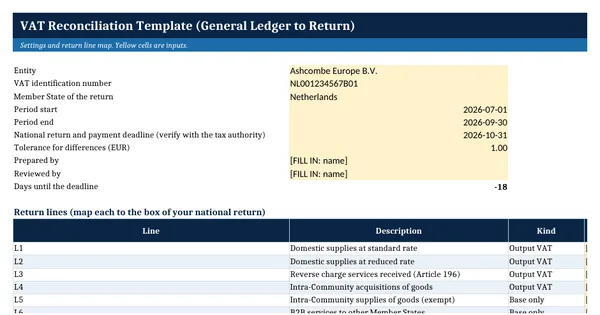
- Registrations table and a tax code table with 10 worked codes, each with its rate basis, Directive reference and return line
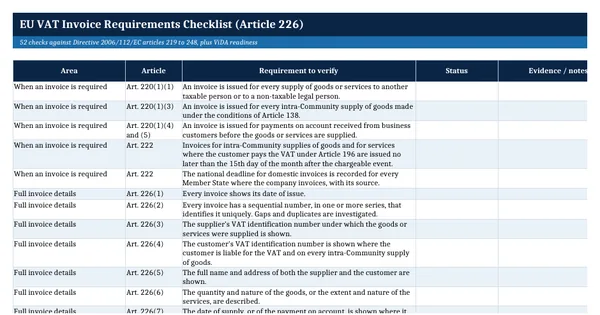
- Invoicing rules built on Articles 219 to 230 of Directive 2006/112/EC, including the 15th day deadline and simplified invoices
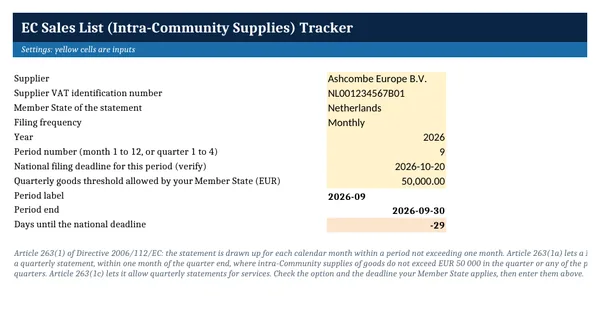
- Customer VAT number checks in VIES and the Article 138(1a) link to the EC Sales List
- Cross-border sales rules for goods, B2B services, the EUR 10 000 threshold and the Union OSS
- Monthly close calendar table with 8 steps, owners and evidence
- Corrections and record retention rules, including the three-year OSS correction window and 10-year OSS records
How to use it
Fill in the registrations table and tax codes from your ERP, then route the manual through the CFO for approval.
Files
- DOCXvat-policy-and-procedures-manual.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What should a VAT procedures manual include?
It should name the VAT registrations and owners, list the tax codes with their legal basis and return lines, set the rules for issuing and checking invoices, explain how customer VAT numbers are validated, describe the return and reconciliation calendar, and set out how errors are corrected and records kept. This template covers each of these.
Do we need to check customer VAT numbers in VIES?
Article 138(1) of the VAT Directive exempts an intra-Community supply of goods only when the customer is identified for VAT in another Member State and has given that number to the supplier. Checking the number in the Commission's VIES service before invoicing, and keeping the result, is the usual way to show this.
How long must VAT records be kept?
For domestic invoices, Article 247 of the VAT Directive lets each Member State set the storage period, so it differs by country and is confirmed per entity. For the One Stop Shop, the Commission's guide says records are kept for 10 years from the end of the year of the transaction.