

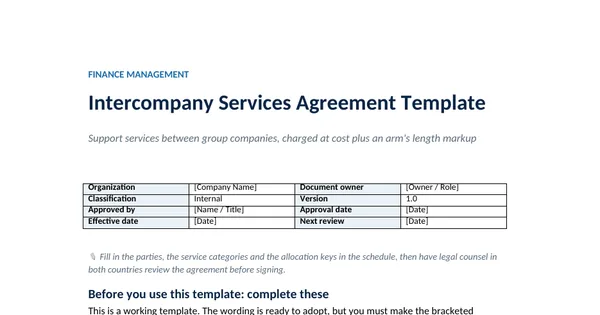
 Word document preview
OECD transfer pricing and Pillar Two
Intercompany Services Agreement Template
3 free downloads per account. Just your email and a 6-digit code.
About this template
An intercompany services agreement is the contract under which one group company provides support services such as accounting, payroll, IT or legal work to other group companies, and charges for them. Tax authorities and auditors expect a written agreement behind every recharge, because it shows what was provided, how the fee is worked out and that the recipient agreed to pay it.
This template is a full agreement with a service schedule, a cost plus fee clause, allocation keys, invoicing, taxes, records, year-end adjustments and term. The fee mechanism follows the simplified approach for low value-adding intra-group services in Chapter VII, Section D of the OECD Transfer Pricing Guidelines, including the 5% markup, the exclusion of shareholder activities and the documentation the OECD text lists. It is not legal advice.
Who it is for
The controller or group tax lead told by the auditor or a tax authority that the recharges between group companies have no written agreement behind them.
What is inside
- 12 numbered sections, from purpose, parties and definitions to signatures
- Service schedule table with 6 service categories, what each includes and excludes, and its allocation key
- Fee clause built on cost plus: pooled costs by allocation key, a 5% markup for low value-adding services and pass-through costs at cost
- Worked annual fee table for an invented UK recipient, with a total fee of USD 743,835
- Exclusion of shareholder activities and duplicated services, in line with Chapter VII of the OECD Guidelines
- Records clause that lists the documentation the OECD simplified approach expects
- Year-end true-up and transfer pricing adjustment clause, signature block and a 7-item checklist
How to use it
Fill in the parties, the service categories and the allocation keys in the schedule, then have legal counsel in both countries review the agreement before signing.
Files
- DOCXintercompany-services-agreement-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Do group companies need a written agreement for intercompany services?
Chapter VII of the OECD Transfer Pricing Guidelines lists written contracts or agreements for the provision of services among the documents a group should prepare when it uses the simplified approach for low value-adding services. More generally, a signed agreement is the first evidence a tax auditor asks for when it reviews a recharge. Local law decides the form.
What markup applies to intercompany services?
For services that meet the OECD definition of low value-adding intra-group services, the simplified approach in paragraph 7.61 of the Guidelines uses a markup of 5% of the relevant cost, without a benchmarking study. Other services need a markup supported by comparables. Not every country has adopted the simplified approach, so check local rules.
Which costs should not be recharged?
Chapter VII says shareholder activities, such as costs of the parent's own legal structure, its consolidated reporting and investor relations, are borne by the shareholder and not charged. Services that merely duplicate what the recipient already does for itself are generally not charged either. The template excludes both in the service schedule.
More OECD transfer pricing and Pillar Two templates
OECD transfer pricing and Pillar Two
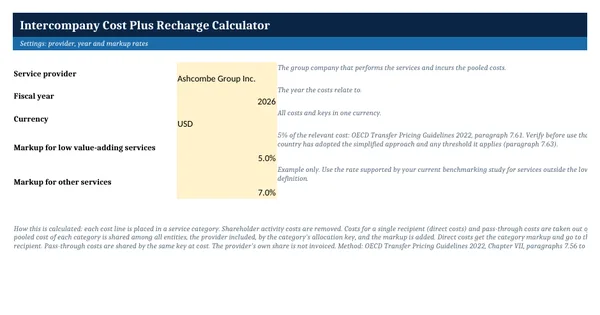
Intercompany Cost Plus Recharge Calculator
OECD transfer pricing and Pillar Two
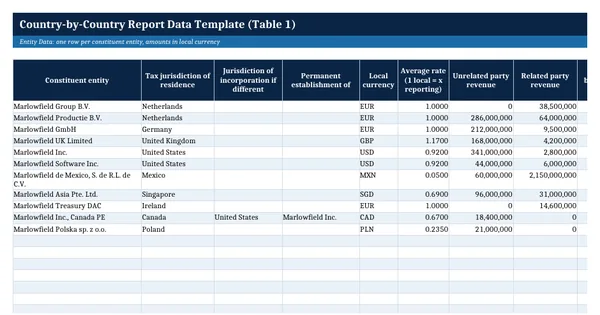
Country-by-Country Report Data Template (Table 1)
OECD transfer pricing and Pillar Two
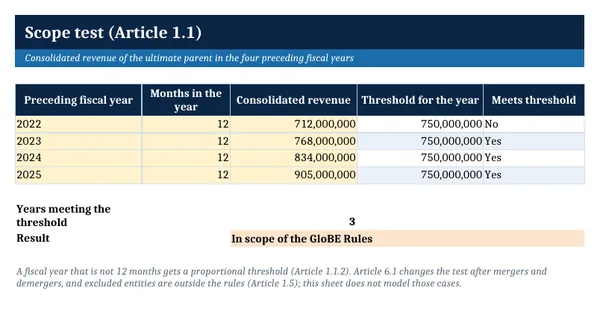
Pillar Two GloBE Effective Tax Rate Calculator (Simplified)
OECD transfer pricing and Pillar Two