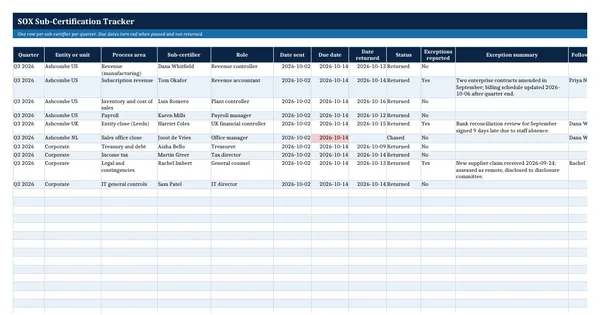
 Excel workbook preview
SOX Sub-Certification Tracker
3 free downloads per account. Just your email and a 6-digit code.
About this template
Sub-certifications are internal sign-offs that process owners and entity controllers give before the CEO and CFO sign the certifications required by Rule 13a-14. No rule requires them, but they are the usual way to show that the officers' statements rest on facts from the people closest to the numbers. This tracker records who was asked, when the answer came back and what each person reported.
The main sheet holds one row per sub-certifier per quarter, with formulas for days late and a status colour. A Statements sheet gives ten plain-language sub-certification statements, each mapped to the paragraph of the officer certification it supports. That certification wording is set in Item 601(b)(31) of Regulation S-K. A Summary sheet counts returns and exceptions per entity for the quarter you choose.
Who it is for
The SOX lead or assistant controller who must show the CFO, before signing the 302 certification, that every process owner signed off and every exception was followed up.
What is inside
- Tracker with 10 worked sample rows for one quarter and 20 blank formatted rows
- Dropdowns for status (4 values) and exceptions reported (Yes or No)
- Live days-late formula and a Red, Amber or Green status per row (late or with exceptions = Amber)
- Due dates turn red when passed and the sub-certification is not returned
- Statements sheet with 10 sub-certification statements mapped to the 302 certification paragraphs
- Summary sheet per entity for a quarter you pick: sent, returned, outstanding, exceptions, % returned
- Freeze panes, filters, landscape print fit and a How to use sheet
How to use it
Type the quarter in the Summary sheet, then replace the sample rows with your own sub-certifiers and due dates.
Files
- XLSXsox-sub-certification-tracker.xlsx14 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
Are SOX sub-certifications required by law?
No. Rule 13a-14 requires the principal executive and principal financial officers to sign. Sub-certifications are a company practice that gives those officers support from the people who run the processes. Many auditors and audit committees expect to see them, and the tracker keeps the evidence that they were requested, returned and followed up.
Who should sign a sub-certification?
Usually the owners of significant processes, the controllers of each in-scope entity, the heads of legal, tax, treasury and IT, and anyone who prepares material disclosures. The aim is to cover every source of information that feeds the periodic report and the controls behind it.
What happens when a sub-certifier reports an exception?
The exception is logged, assessed by the SOX lead and the controller, and taken to the disclosure committee. If it points to a control deficiency, it goes to the deficiency log and is evaluated for severity before the officers sign. The tracker records the follow-up owner for each exception.