

 Word document preview
OECD transfer pricing and Pillar Two
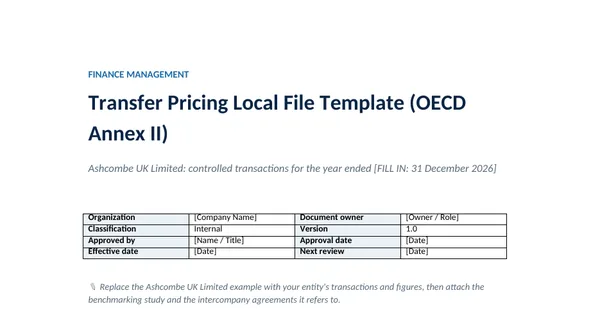
Transfer Pricing Local File Template (OECD Annex II)
3 free downloads per account. Just your email and a 6-digit code.
About this template
A transfer pricing local file documents the material controlled transactions of one entity in one country: what was bought, sold, licensed or lent between group companies, for how much, and why the price is at arm's length. It is the second tier of the documentation described in Chapter V of the OECD Transfer Pricing Guidelines, and it is usually the first document a local tax auditor asks for.
This template follows Annex II to Chapter V of the OECD Transfer Pricing Guidelines (2022 edition). It is worked for an invented UK distributor and assembler buying from its US parent: management structure, business and strategy, a controlled transactions table, a functional analysis, the choice of method and tested party, benchmark results, and a segmented profit and loss that ties to the statutory accounts.
Who it is for
The finance manager of a subsidiary, or the group tax lead, asked by the local tax authority or the auditor for the entity's transfer pricing local file.
What is inside
- 11 numbered sections that follow the Annex II headings: local entity, controlled transactions and financial information
- Management structure table showing to whom local management reports and where
- Controlled transactions table with 5 categories, counterparties, amounts paid or received, agreements and methods
- Functional analysis table comparing the local entity with its parent across 10 functions, risks and assets
- Method selection, tested party and assumptions explained for a TNMM test of a distributor
- Benchmark results table with interquartile range and the tested party result
- Segmented profit and loss table that ties the tested segment to the statutory accounts, plus a 7-item checklist
How to use it
Replace the Ashcombe UK Limited example with your entity's transactions and figures, then attach the benchmarking study and the intercompany agreements it refers to.
Files
- DOCXtransfer-pricing-local-file-template.docx41 KB
Opens in Microsoft Word or Excel, Google Docs or Sheets, and LibreOffice. Built on free, official texts that anyone can read: laws, regulations, standards and guidance published by public bodies. A template to adapt, not legal, tax or accounting advice.
Questions about this template
What goes into a transfer pricing local file?
Annex II to Chapter V of the OECD Guidelines lists three parts: the local entity (management structure, business and strategy, key competitors), the controlled transactions (description, amounts by jurisdiction, counterparties, agreements, functional analysis, method, tested party, comparables and conclusion) and financial information, including a reconciliation to the annual accounts.
What is a tested party in transfer pricing?
The tested party is the entity whose financial result is compared with independent companies when a one-sided method such as the transactional net margin method is used. It is usually the less complex party that owns no unique intangibles, such as a distributor or a contract manufacturer. Annex II asks the local file to name it and explain why.
Can the local file refer to the master file?
Yes. Annex II notes that where the functional analysis in the local file would duplicate information in the master file, a cross-reference to the master file is sufficient. The local file still needs the entity-level detail, the amounts and the transfer pricing analysis for its own transactions.
More OECD transfer pricing and Pillar Two templates
OECD transfer pricing and Pillar Two
Intercompany Services Agreement Template
OECD transfer pricing and Pillar Two
Intercompany Cost Plus Recharge Calculator
OECD transfer pricing and Pillar Two
Country-by-Country Report Data Template (Table 1)
OECD transfer pricing and Pillar Two